
In a corporate compliance framework, what is the primary objective of establishing and maintaining a system of internal controls?
Select an answer to reveal the explanation.
Short Explanation
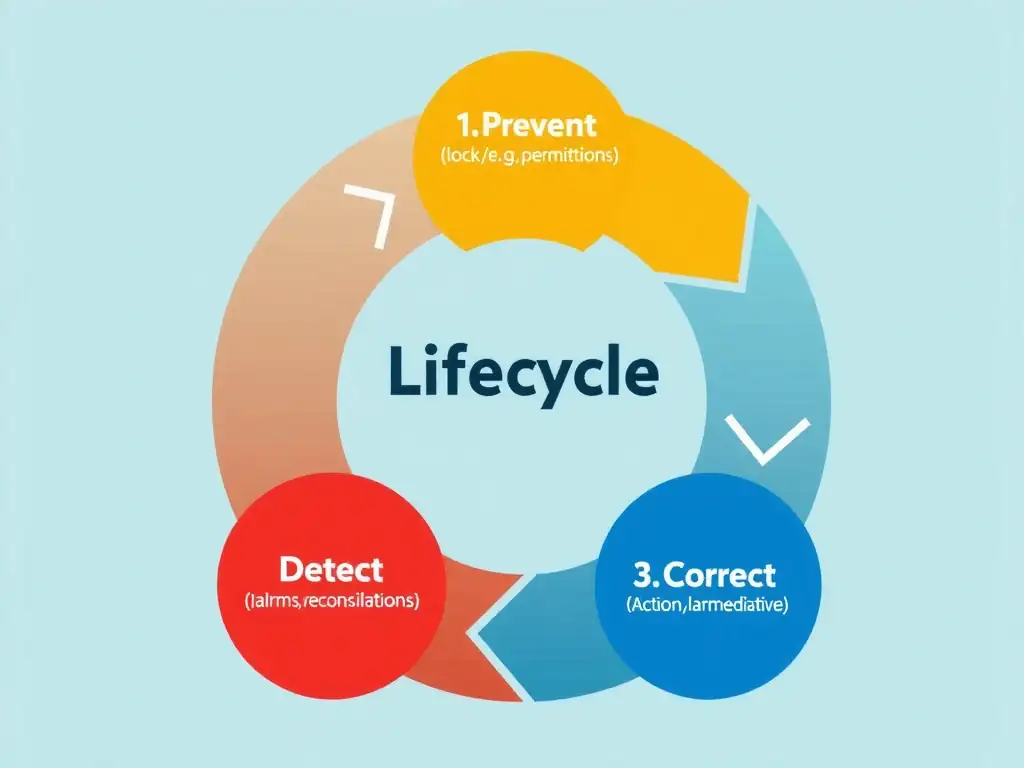
Think of internal controls like guardrails and warning signs on a winding mountain road; they don't stop you from driving or steer the car for you, they prevent you from flying off the cliff, detect slipping, and help you get back on track. In compliance, that means preventing errors, detecting when something goes wrong, and correcting issues before they become disasters. Got it, sweet—let's keep rolling!
Full Explanation
The primary objective of establishing and maintaining a system of internal controls is to provide reasonable assurance that the organization's objectives are met regarding operational efficiency, reliable reporting, and compliance with laws and regulations. To achieve this, internal controls are categorized into three main types: preventive controls, designed to stop errors, fraud, or irregularities before they occur, such as segregation of duties; detective controls, designed to identify errors, fraud, or irregularities after they have occurred, such as reconciliations or audits; and corrective controls, designed to remedy problems discovered by detective controls, such as system patches or training. The choice stating that the objective is preventing, detecting, and correcting errors, fraud, and non-compliance within organizational processes is therefore correct. The choice about streamlining all executive business decisions and overriding operational risks is incorrect because internal controls do not make business decisions; they establish the boundaries, procedures, and checks within which business decisions must be made by authorized managers. The choice about maximizing short-term profitability and revenue generation through aggressive cost-cutting is incorrect because while efficient controls can protect value, their primary purpose is risk mitigation and integrity, not maximizing short-term profits at all costs, which could lead to compliance failures. The choice about guaranteeing the legal department is fully staffed and capable of defending the company in litigation is incorrect because the presence of internal controls is focused on operational processes throughout the company, not merely ensuring the legal department has resources or capacity for litigation defense.