
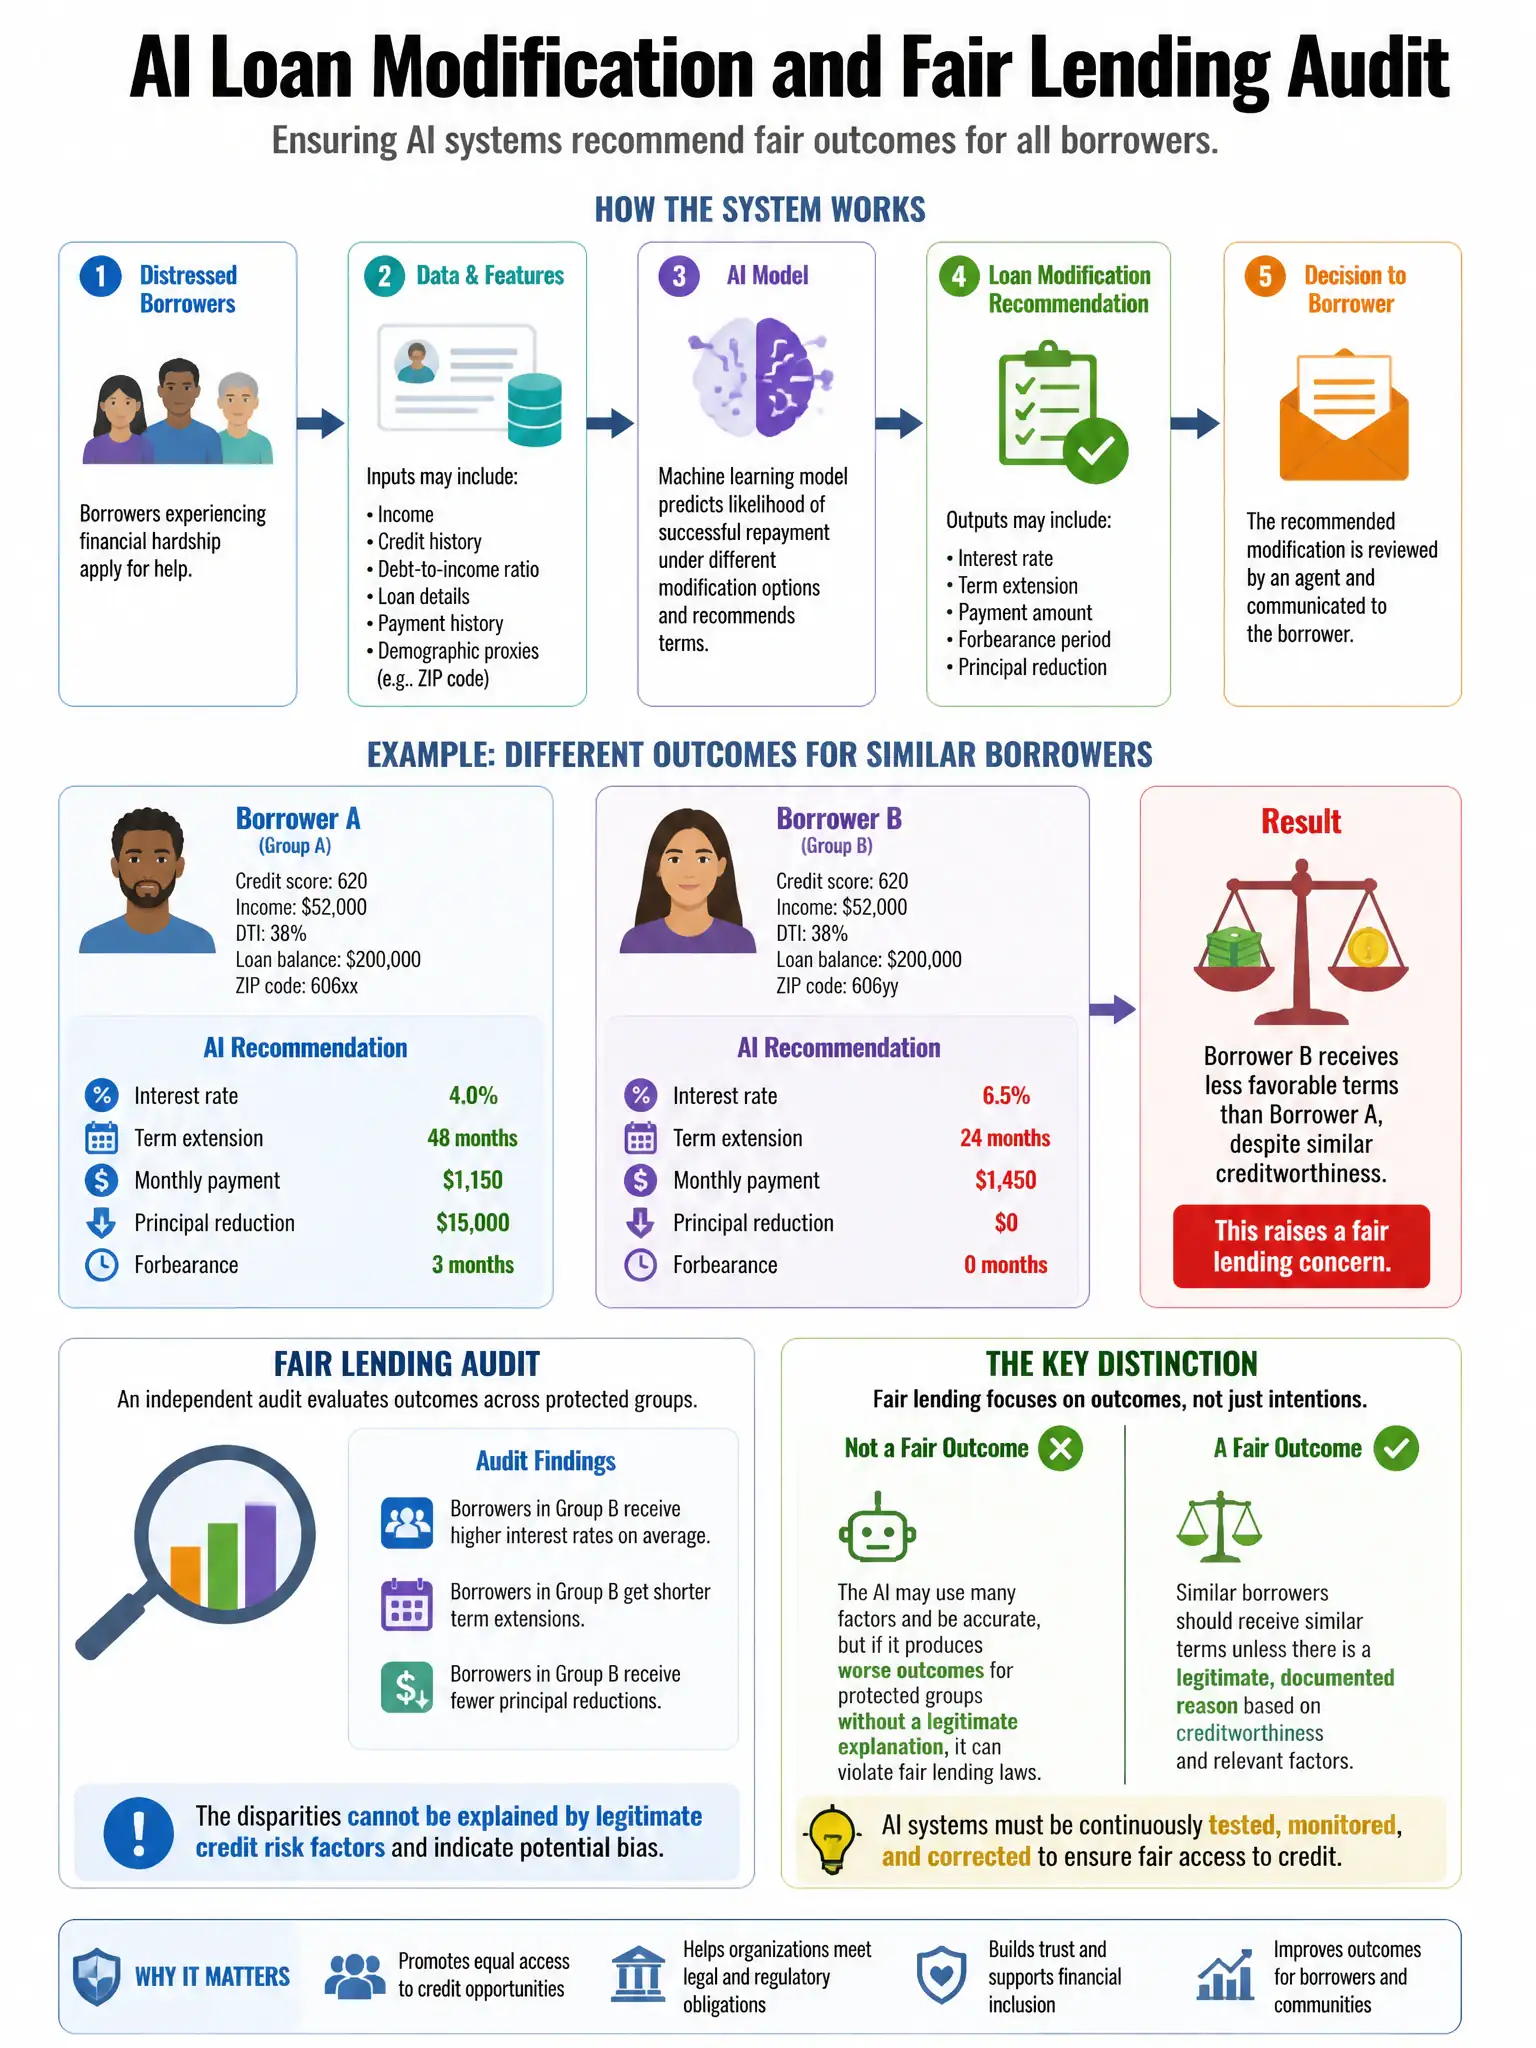
An AI system generates loan modification recommendations for distressed borrowers. A fair lending audit reveals that the model recommends less favorable modification terms for borrowers in predominantly Black zip codes, even after controlling for credit score and loan-to-value ratio. Under which legal framework would this finding MOST likely be investigated?
Select an answer to reveal the explanation.
Short Explanation
Here's the deal — if your model gives Black borrowers worse loan modification terms, you're in Fair Housing Act and Equal Credit Opportunity Act territory. Zip code as a racial proxy is classic redlining, and those laws cover credit terms and modifications.
Full Explanation
The correct framework is the Fair Housing Act and Equal Credit Opportunity Act because discriminatory loan modification terms based on race, even when proxied through zip code, in residential mortgage lending fall under those statutes, which prohibit discrimination in all aspects of credit transactions including modifications. The use of zip code as a racial proxy is a recognized form of redlining under Fair Housing Act enforcement. The Computer Fraud and Abuse Act claim is wrong because it addresses unauthorized computer access, not algorithmic discrimination. The General Data Protection Regulation claim is wrong because it is a privacy regulation, and zip code is not a protected attribute under that regulation per se. The Sarbanes-Oxley Act claim is wrong because it addresses financial reporting integrity, not lending discrimination.