
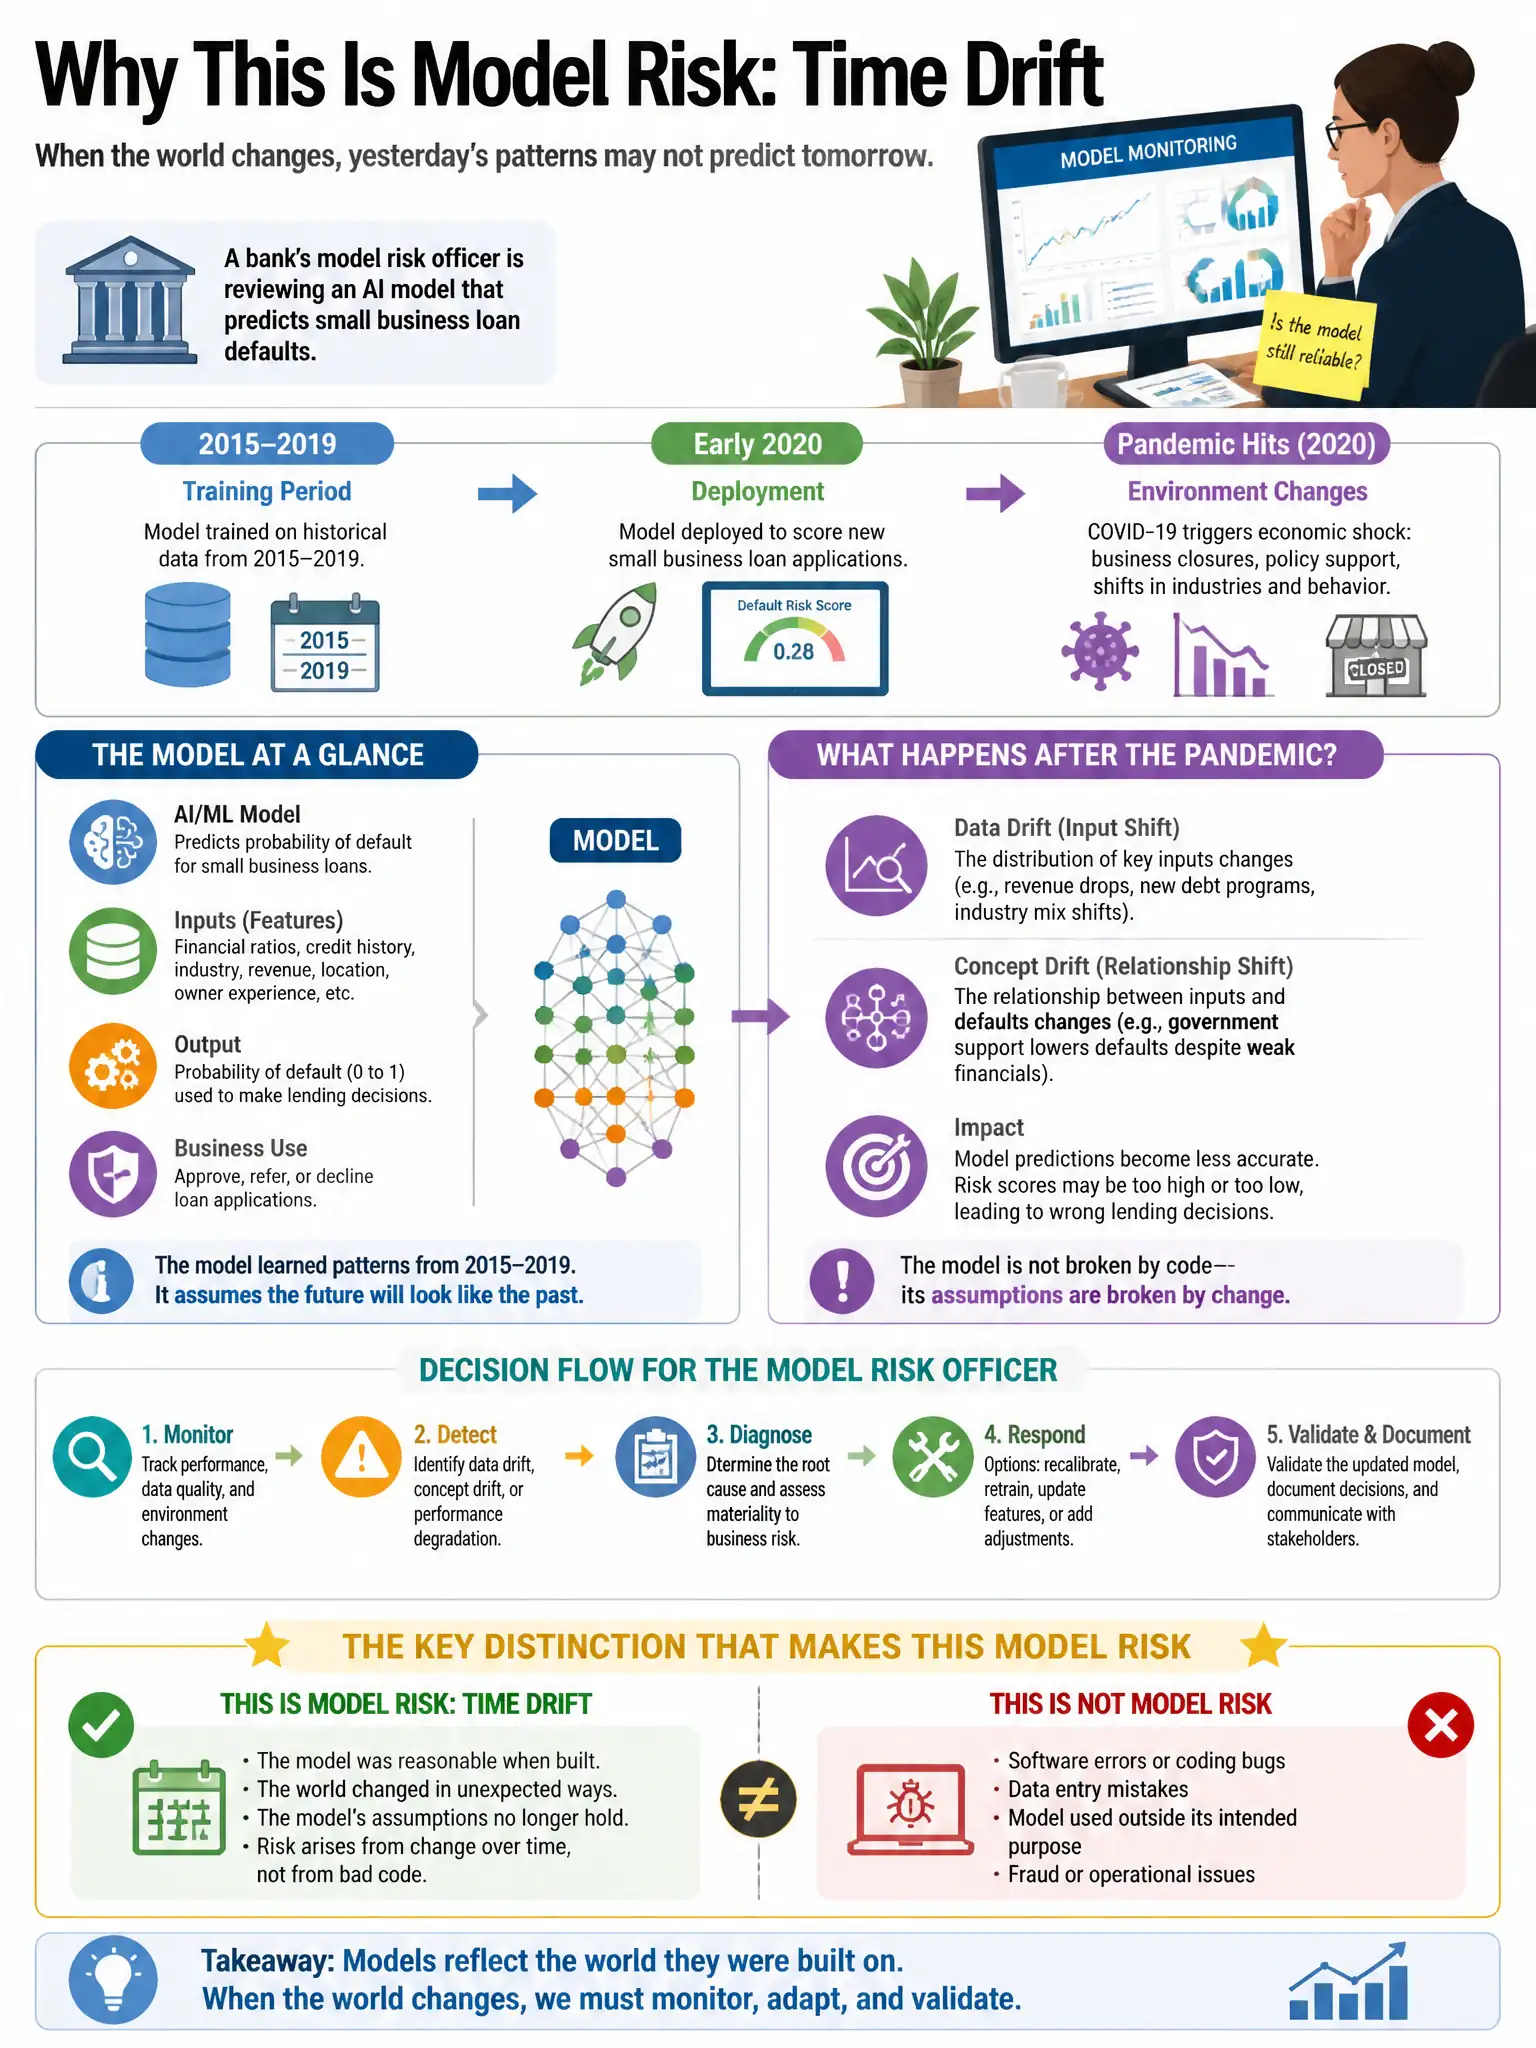
A bank's model risk officer is reviewing an AI model that predicts small business loan defaults. The model was trained on data from 2015–2019 and deployed in early 2020. During a post-deployment audit, performance has deteriorated sharply. The most plausible explanation is that the COVID-19 pandemic drastically changed default patterns. What type of model risk does this MOST represent?
Select an answer to reveal the explanation.
Short Explanation
Here's the deal — you're looking at concept drift because the pandemic changed what the features actually mean for default risk. The relationships the model learned from 2015–2019 stopped holding after the external shock.
Full Explanation
Concept drift is correct because an external economic shock like the pandemic fundamentally changes the relationship between predictive features and outcomes. The model's learned associations, such as industry type predicting low default risk, became invalid post-pandemic. The overfitting explanation would have been visible in pre-deployment validation, not only after the external shock. The data-poisoning explanation would require an intentional attacker. The implementation-error explanation would cause performance problems from the start of deployment.