
An alternative data team at a real estate investment trust (REIT) wants to generate alpha by predicting same-store NOI growth before it is reported. They have access to high-cadence satellite imagery, mobile foot traffic data, and building permit filings. Which data integration strategy is MOST likely to produce statistically significant alpha, and why?
Select an answer to reveal the explanation.
Short Explanation
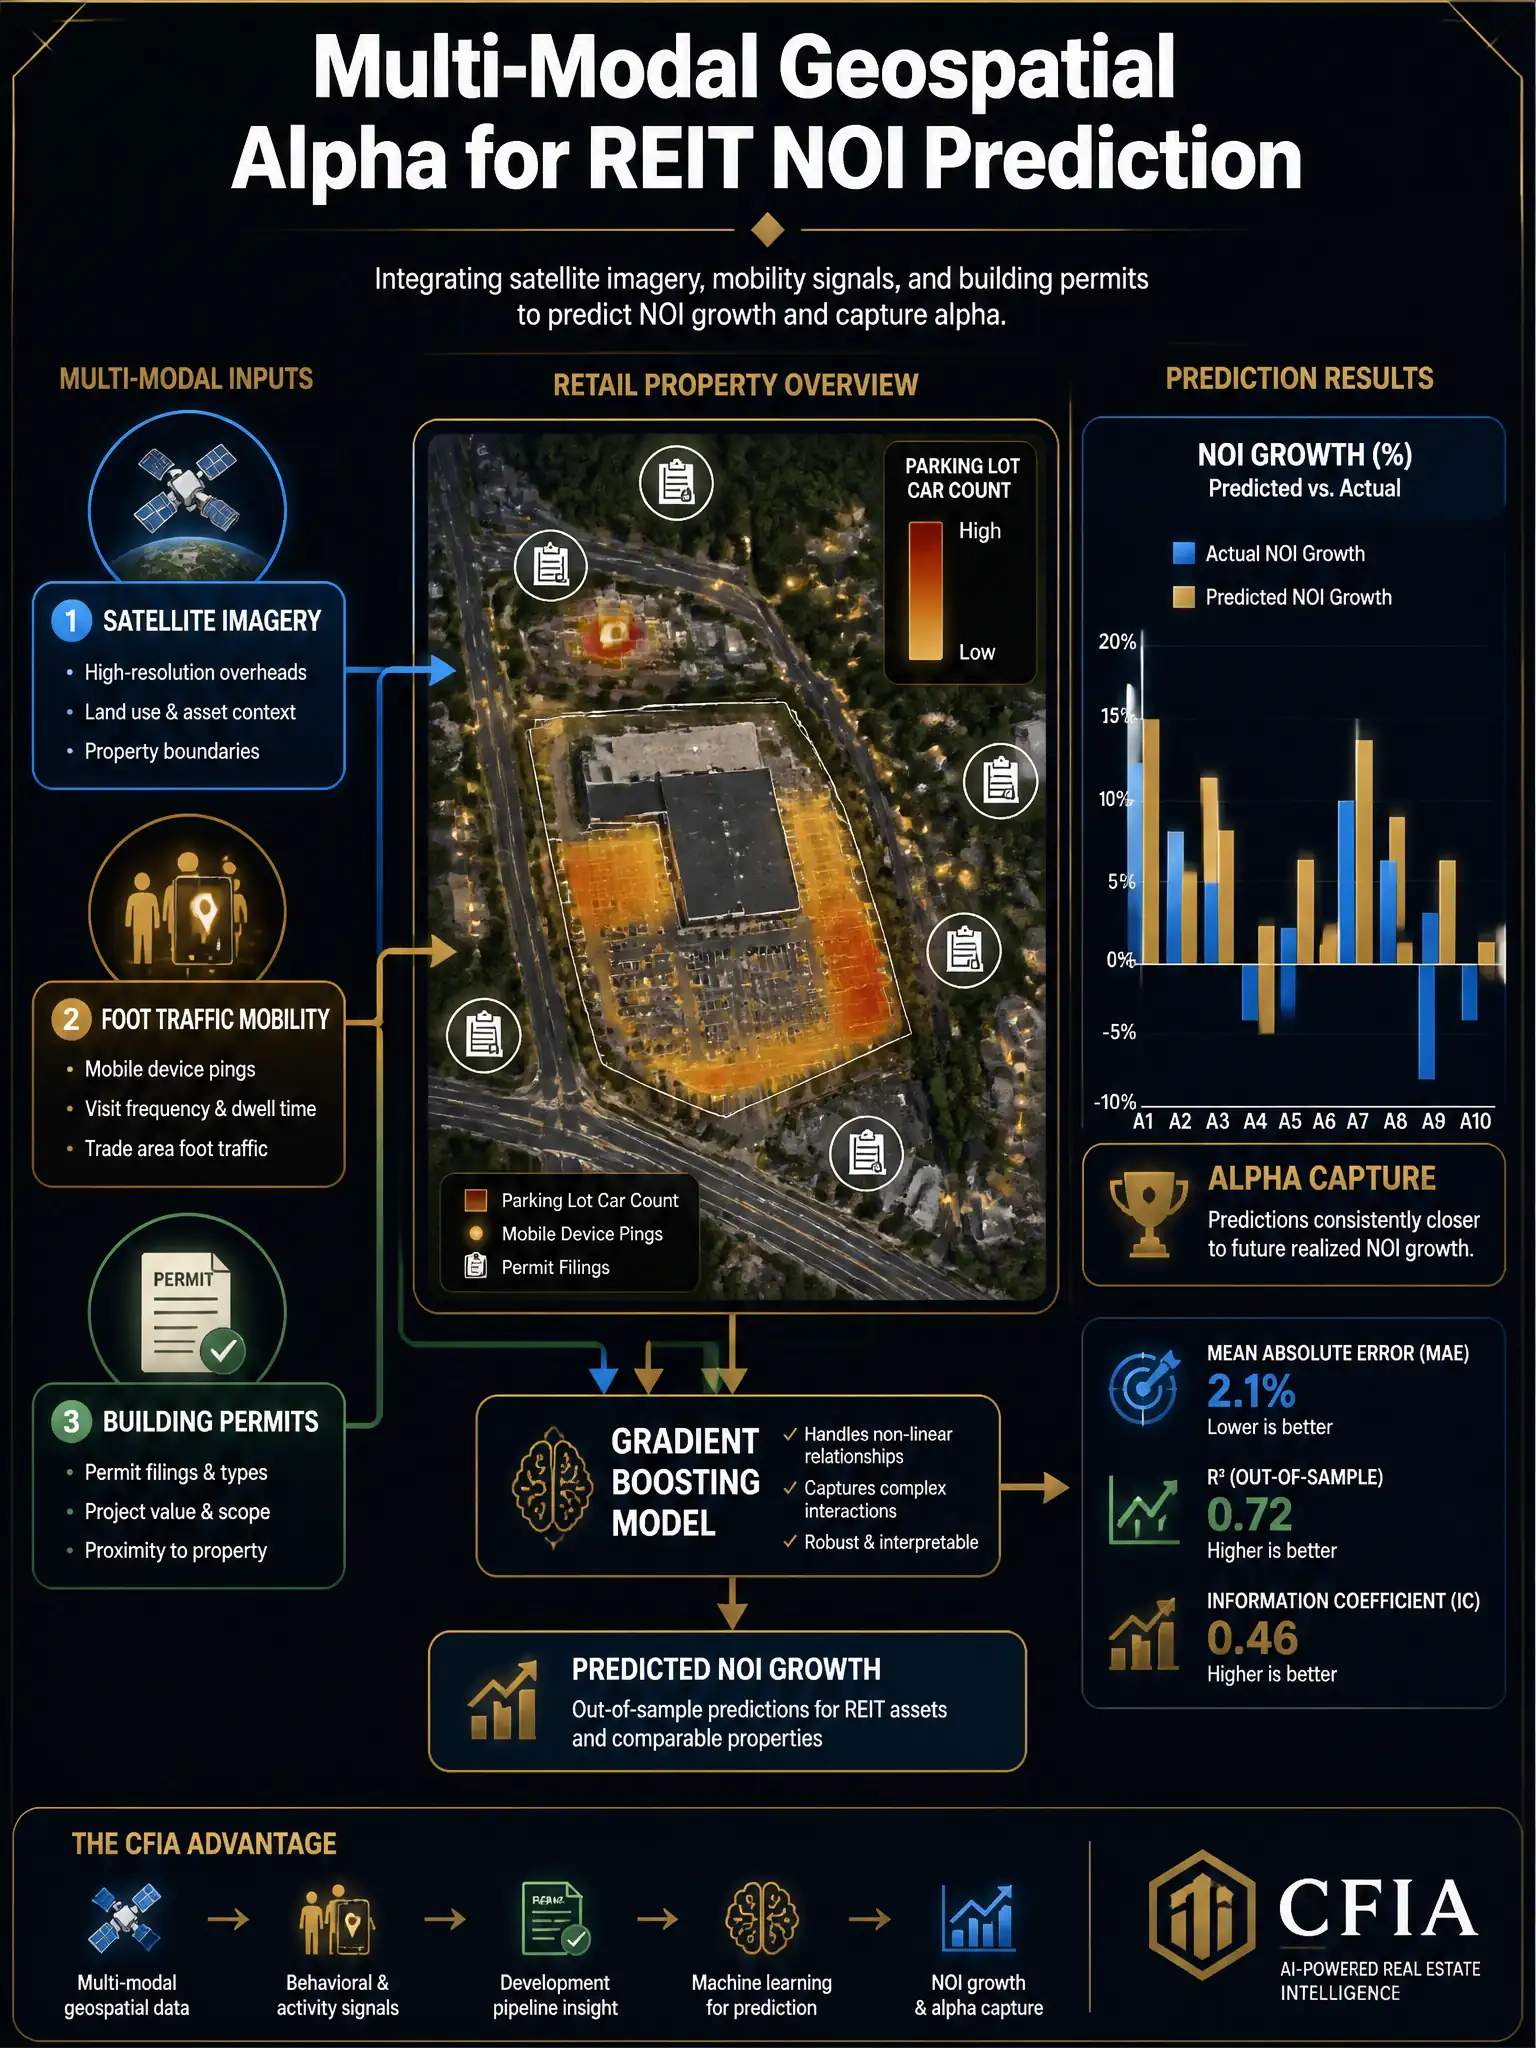
You'll get the strongest edge by fusing satellite parking-lot occupancy, mobile foot traffic, and permit filings into one property-level feature set, then training a gradient boosting model. One signal alone misses half the story; together they capture demand, supply, and physical conditions before NOI is reported.
Full Explanation
The fused multi-modal feature set combining satellite-derived parking lot occupancy metrics, foot traffic mobility signals, and permit data is correct because geospatial alpha generation in real estate reaches its highest predictive power when complementary data streams capture different aspects of property performance at different time horizons. Satellite imagery processed with computer vision (car counting in parking lots, roof HVAC unit monitoring, loading dock activity) provides a persistent, high-frequency proxy for occupancy and tenant health. Mobile foot traffic (from anonymized SDK panel data) captures consumer visitation with latency measured in days. Building permit filings — for both the subject property and competing developments within a defined trade area — provide forward-looking supply pressure signals.
Gradient boosting models (XGBoost, LightGBM) are particularly well-suited to this type of structured heterogeneous feature set because they handle missing data gracefully, model non-linear interactions between features, and provide feature importance scores that allow analysts to understand which signals are driving predictions — critical for investment committee presentations.
The property-level granularity point is important: REITs report same-store NOI at the portfolio level, but the predictive signal is richest when modeled at the individual asset level, then aggregated. This allows the model to identify which specific properties are outperforming or underperforming the portfolio mean — information that is valuable for both position sizing in REIT securities and for direct real estate investors doing asset-level underwriting.
Analyzing building permit filings in isolation provides only one dimension — supply pipeline — and misses demand-side signals entirely. Government data quality is high, but single-source models underperform in real estate because supply and demand are jointly determined. Using mobile foot traffic data exclusively ignores competitive dynamics and physical property conditions. Purchasing consensus NOI estimates from sell-side analysts and reweighting them using local CPI inflation data is not alpha generation — it is information recycling, and consensus estimates are already reflected in market prices by the time they are published.