
A portfolio manager uses a vendor-supplied sentiment score derived from news articles to tilt sector weights in a multi-asset fund. The score ranges from -1 (very negative) to +1 (very positive) and is updated daily. She notices that the sentiment score for energy stocks becomes sharply positive three trading days before oil price spikes. Which of the following BEST describes the risk she must assess before increasing reliance on this signal?
Select an answer to reveal the explanation.
Short Explanation
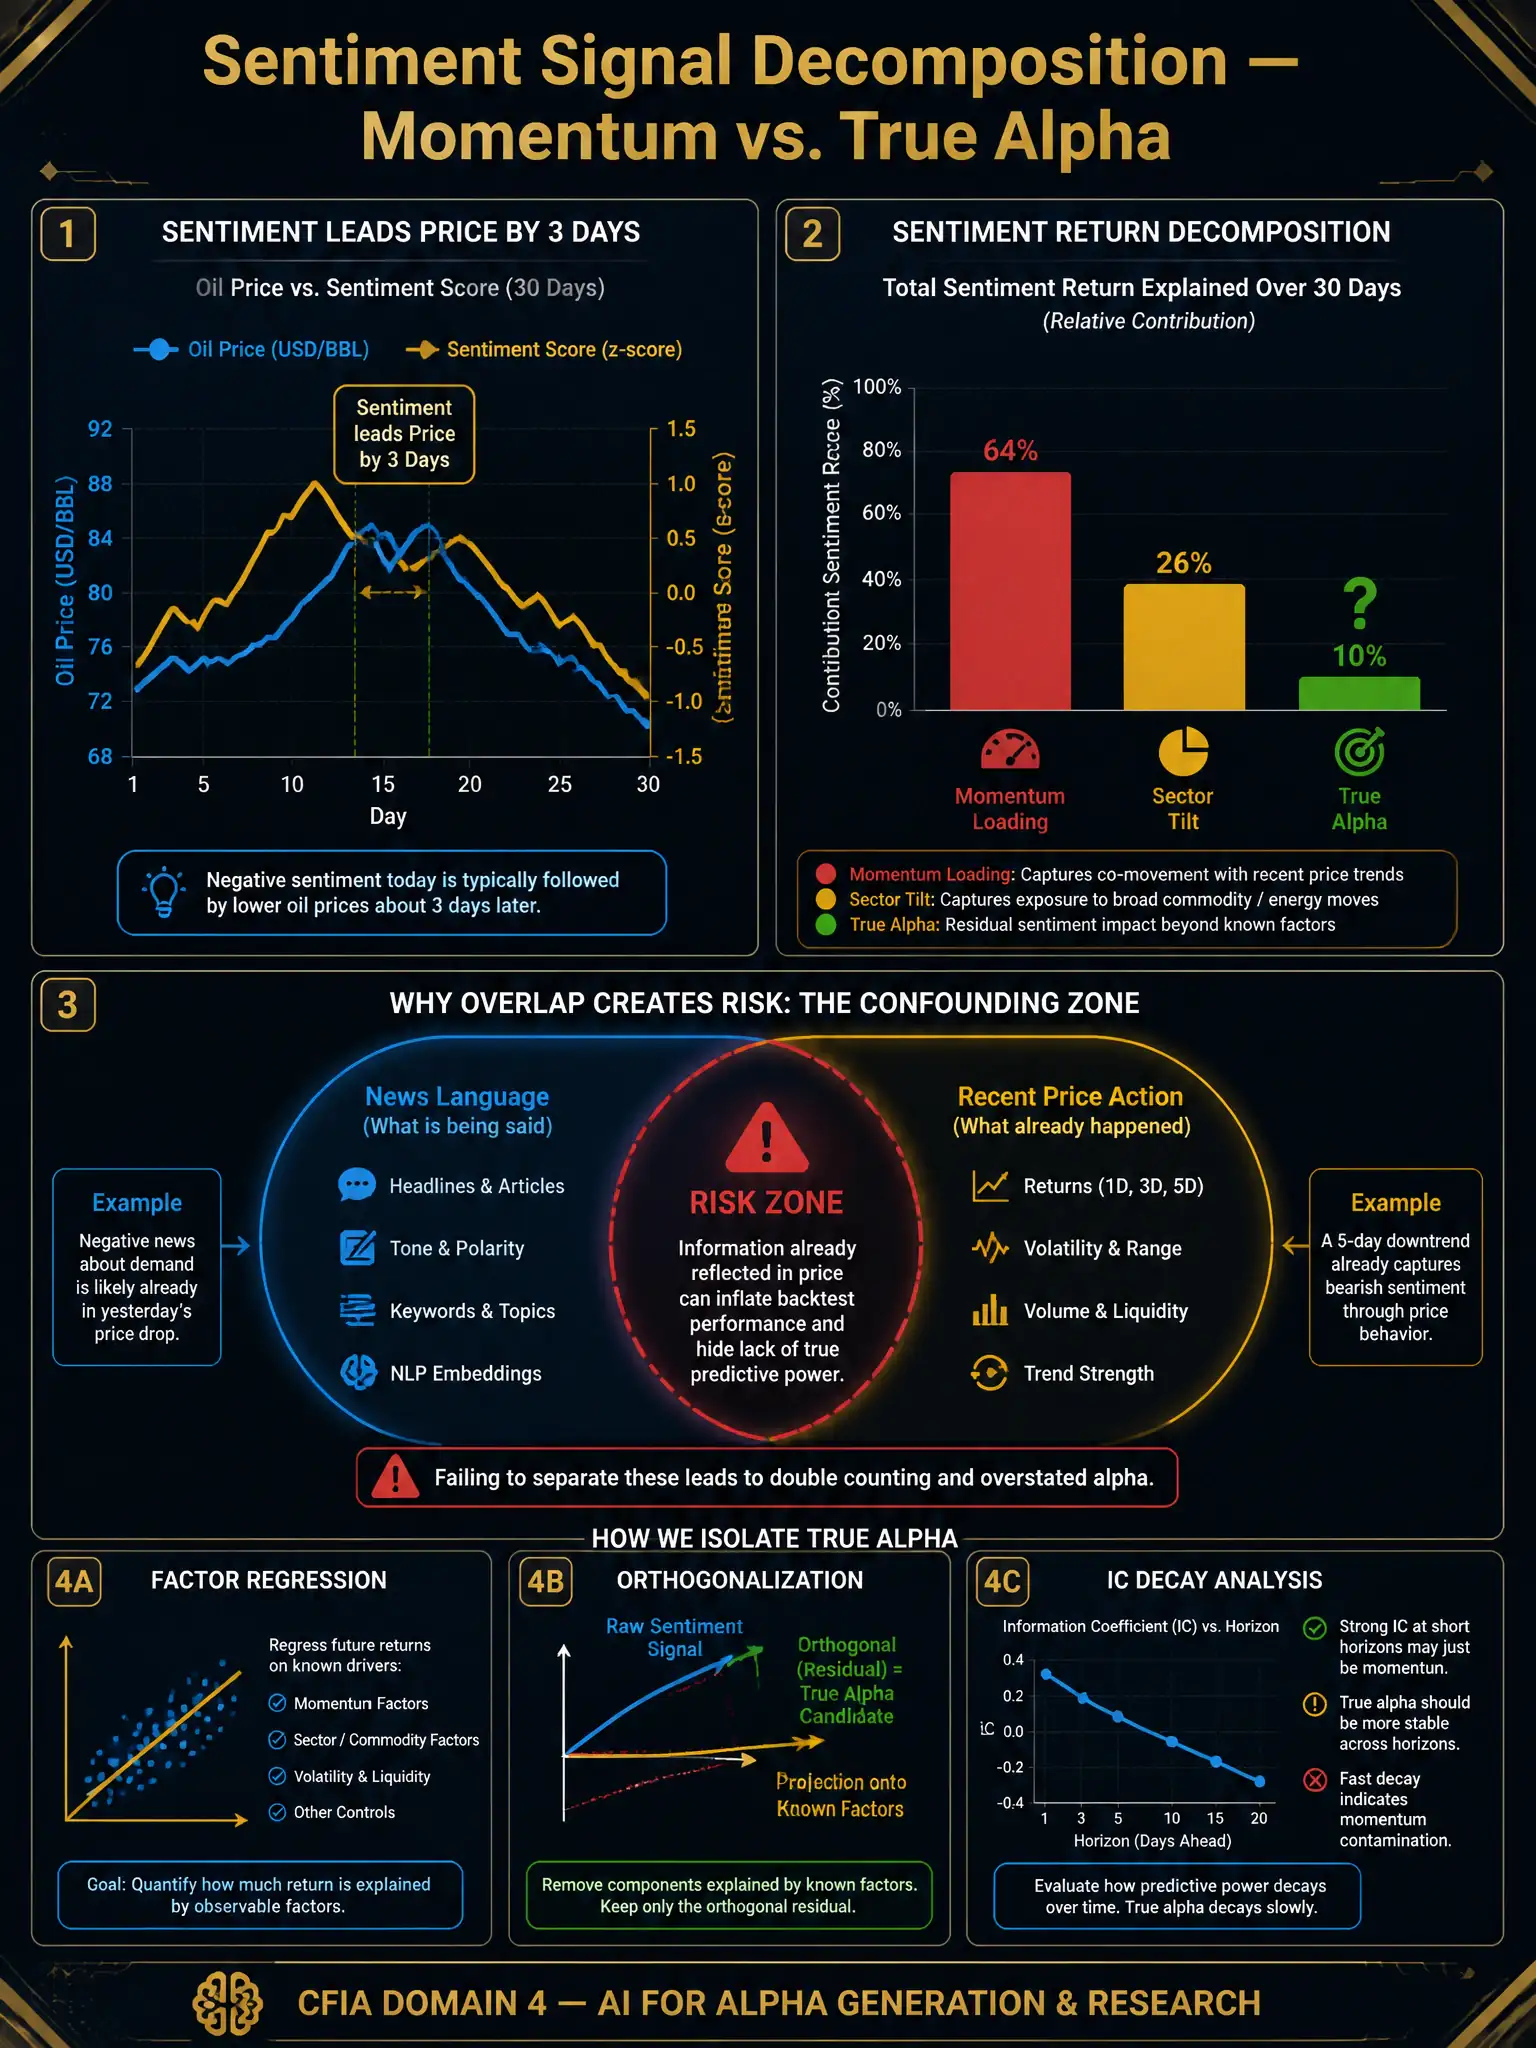
What looks like a three-day leading indicator might just be momentum wearing a disguise. News articles often discuss recent price action, analyst upgrades after stock moves, or supply tightening that markets already partially priced in. If the vendor's model is scoring momentum-tinted language, you're not getting a new signal; you're getting your existing momentum factor with extra steps and a higher licensing fee.
Full Explanation
The critical risk is that the sentiment signal may not be informationally independent from price momentum. Many news-based NLP models are trained on or calibrated against historical return data, meaning they learn to recognize language patterns that co-occur with price increases. When energy prices rise, journalists describe supply constraints, demand recovery, and OPEC discipline — language that a sentiment model trained on return-correlated text would score as positive. If the three-day lead time reflects journalists writing forward-looking pieces about futures curves or rig counts, which may reflect genuine fundamentals, the signal may be valid. If it reflects momentum-adjacent coverage of recent oil price moves with a publication lag, the apparent lead disappears on a risk-adjusted basis.
The reverse-causality concern — rising oil prices may cause financial journalists to write positive energy articles, meaning the sentiment is a lagging rather than leading indicator — is partially relevant but describes a lagging signal, which contradicts the observed three-day lead time. True lagging indicators would score positive after oil spikes, not before.
The Regulation FD concern — that the sentiment score violates Regulation FD if it aggregates analyst comments from post-earnings calls — is a compliance concern for material non-public information shared selectively by companies; it does not apply to aggregated news sentiment from public articles.
The claim that news-based sentiment scores are inherently unreliable because language models cannot distinguish between positive financial events and positive geopolitical events is a model capability critique, not a structural risk. Modern financial NLP models with domain-specific fine-tuning routinely disambiguate these contexts; the claim is an overgeneralization that would make it an incorrect choice.
The correct due diligence protocol is to decompose the sentiment signal into its component parts: run a factor regression controlling for momentum, value, and quality exposures to determine how much of the sentiment signal's return is attributable to known factor loadings versus true idiosyncratic alpha. If the alpha t-statistic collapses after controlling for a 1-month momentum factor, the signal is redundant.