
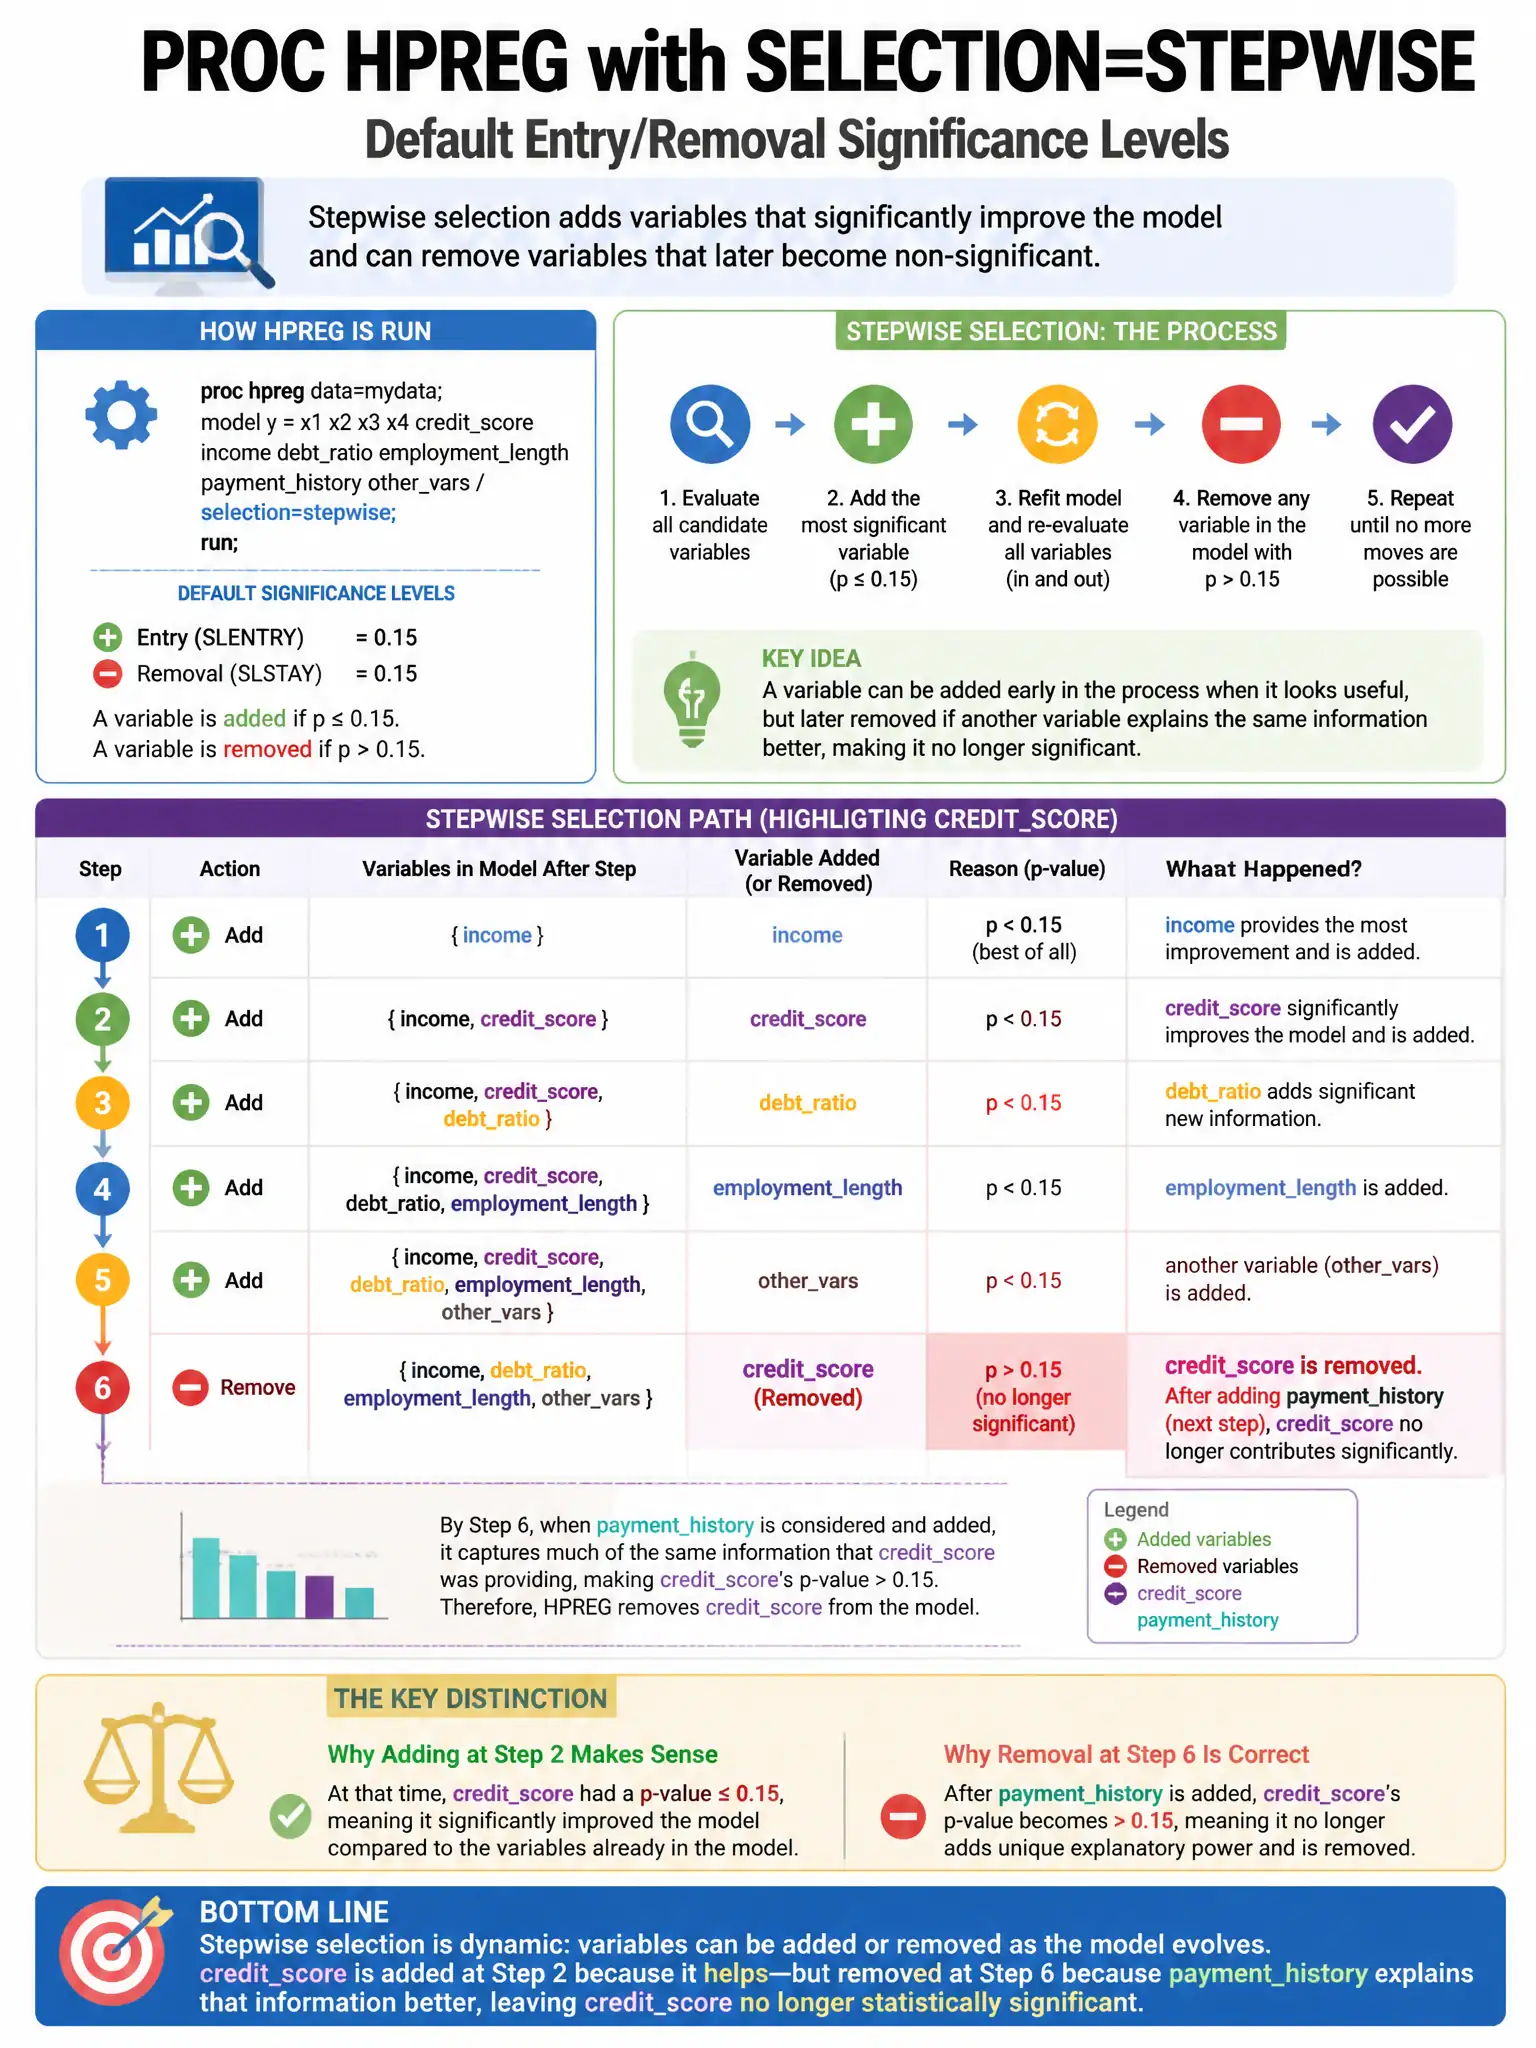
PROC HPREG is run with SELECTION=STEPWISE and the default entry/removal significance levels. A variable 'credit_score' is added at step 2 but then removed at step 6 when 'payment_history' enters. At step 9, 'credit_score' re-enters after 'debt_ratio' removes 'payment_history'. What is the most appropriate modeling response to this stepwise cycling?
Select an answer to reveal the explanation.
Short Explanation
Here's the deal — stepwise cycling is a red flag for multicollinearity, not proof that one variable is king. You should check VIFs, consider ridge or LASSO, and use business sense instead of trusting the stepwise path.
Full Explanation
Stepwise cycling is a diagnostic signal of multicollinearity — when predictors are correlated, their partial contributions change as correlated predictors enter or leave the model. The appropriate response is to investigate the correlation structure with VIFs or a correlation matrix, consider regularization alternatives such as ridge regression or LASSO, or use subject-matter expertise to select among correlated predictors. The option saying cycling confirms 'credit_score' is the single most important predictor and should always be forced into the model is wrong because cycling indicates instability, not definitive importance. The option recommending a larger sample size to stabilize the stepwise path is wrong because sample size does not eliminate the fundamental collinearity issue. The option recommending SLENTRY=0.001 and SLSTAY=0.001 to tighten the significance thresholds and eliminate cycling is wrong because tighter thresholds may reduce cycling but can also exclude important predictors and don't address the underlying collinearity.