
Which regularization technique simultaneously performs variable selection by producing exactly zero coefficients for irrelevant features?
Select an answer to reveal the explanation.
Short Explanation
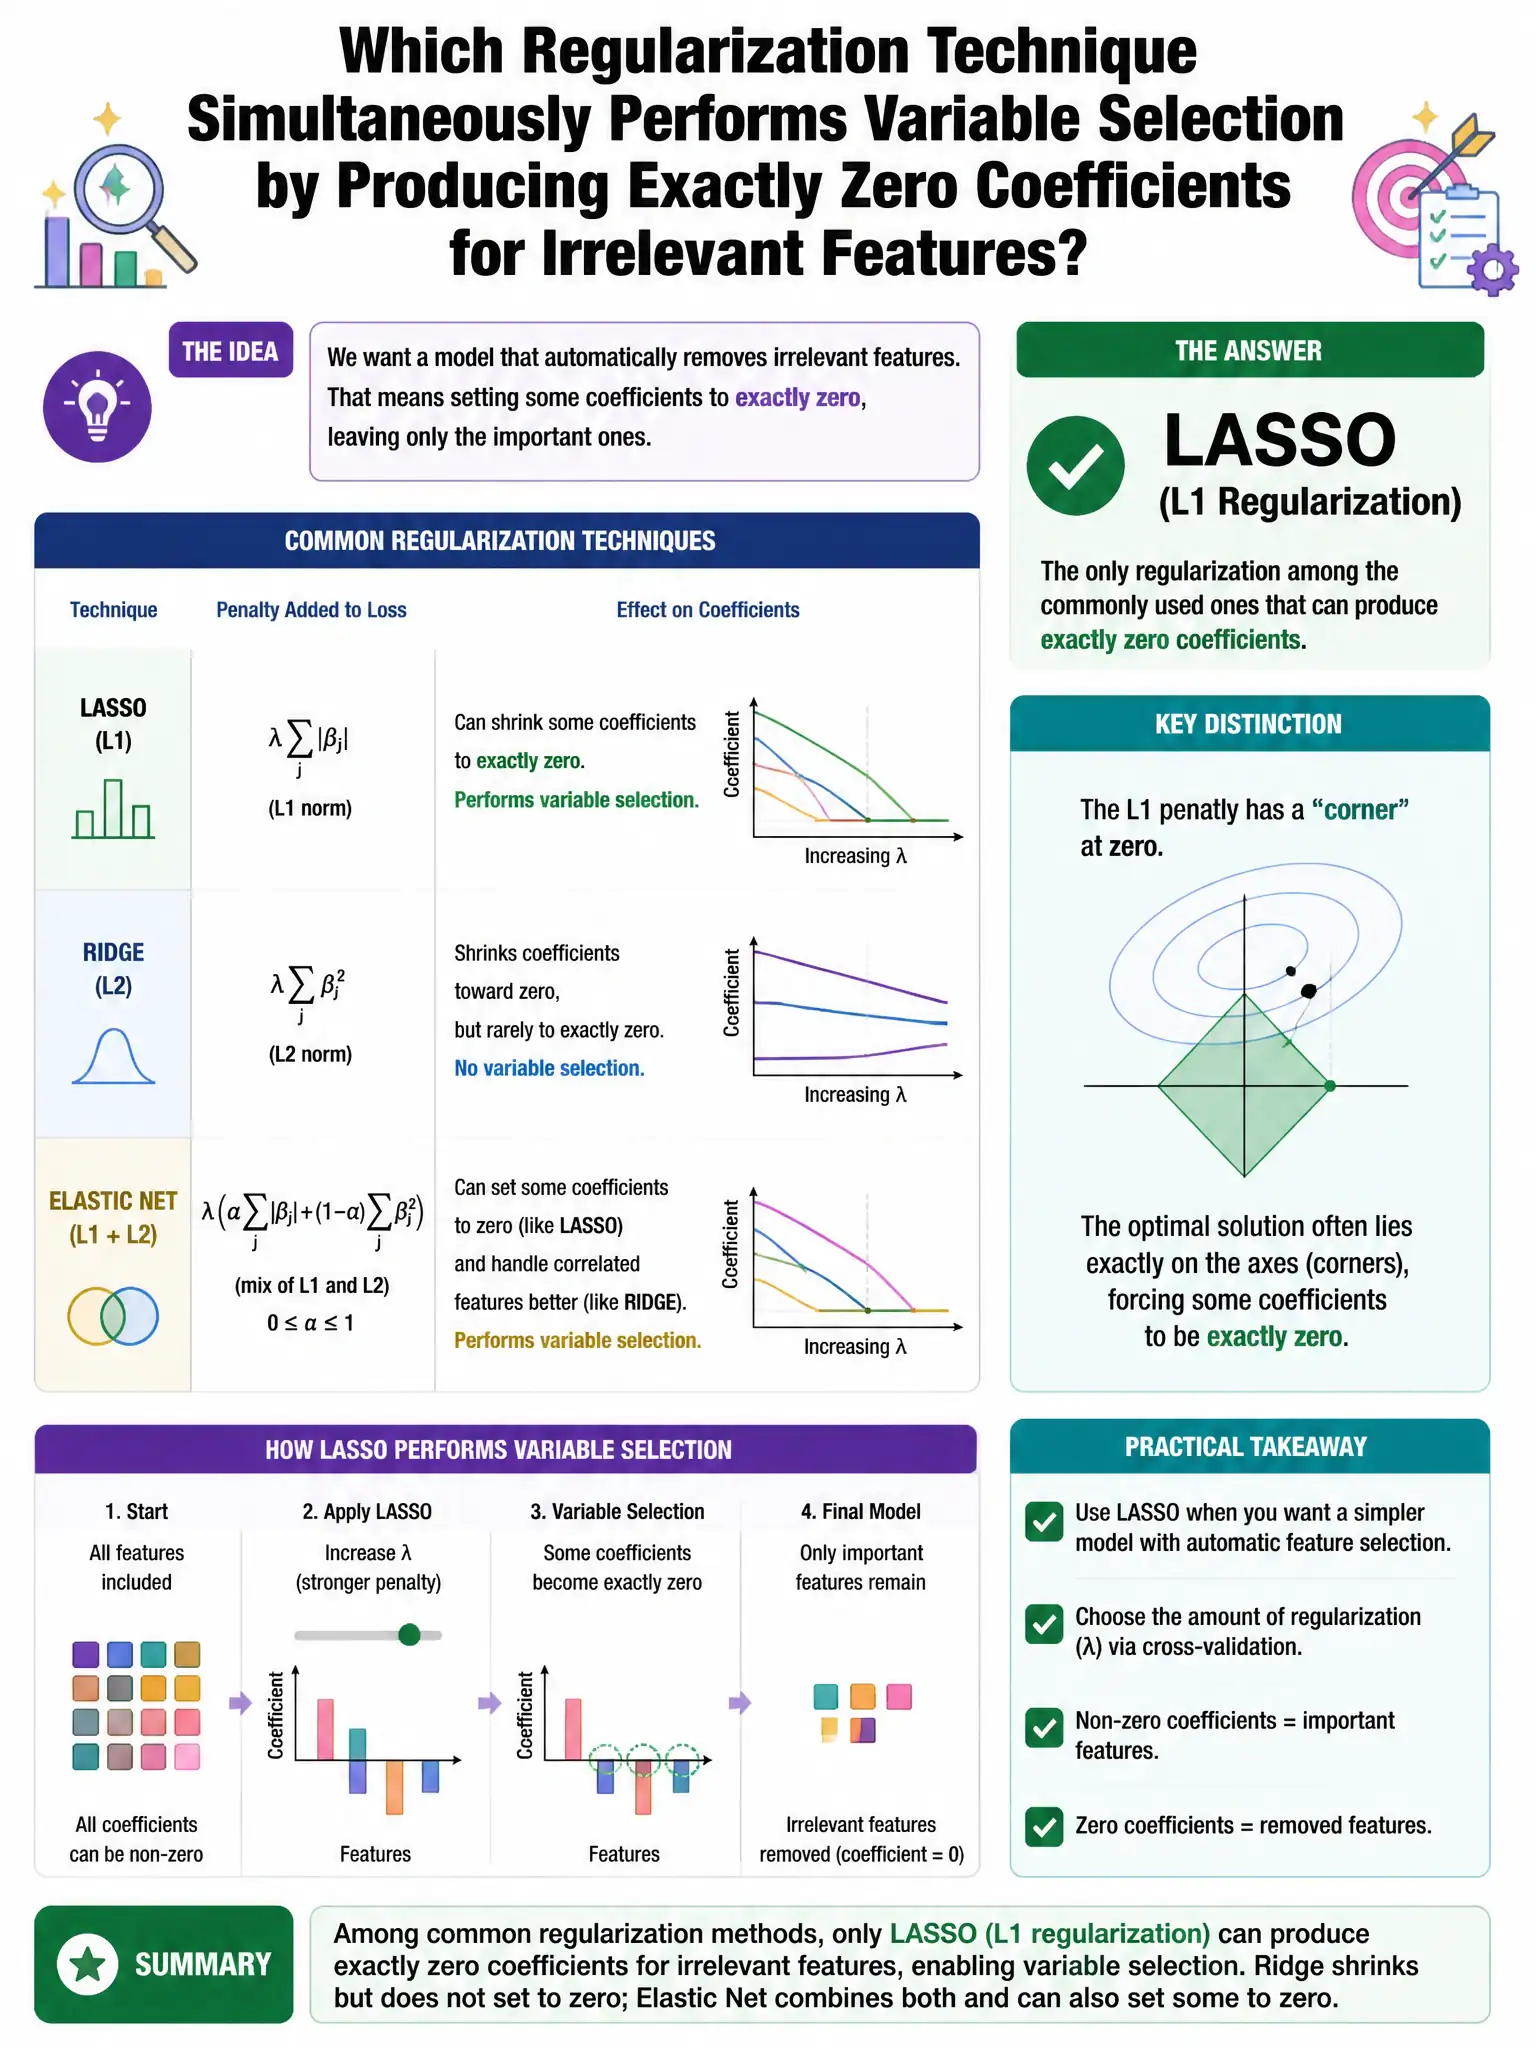
Here's the deal — you get exactly zero coefficients with Lasso regularization because its L1 penalty has a diamond-shaped constraint region with corners on the coordinate axes, so the optimum can land on a corner and zero out irrelevant features. Ridge regularization only shrinks coefficients toward zero, not exactly to zero.
Full Explanation
Lasso (L1) regularization is correct because its L1 penalty has a diamond-shaped constraint region with corners on the coordinate axes, so the optimum can land on a corner and set irrelevant coefficients exactly to zero. Ridge (L2) regularization is wrong because it shrinks coefficients toward zero but not exactly to zero. Elastic Net regularization is wrong because it combines L1 and L2 and can produce sparsity, but is less aggressive. Dropout regularization is wrong because it is a neural network technique unrelated to coefficient selection.