
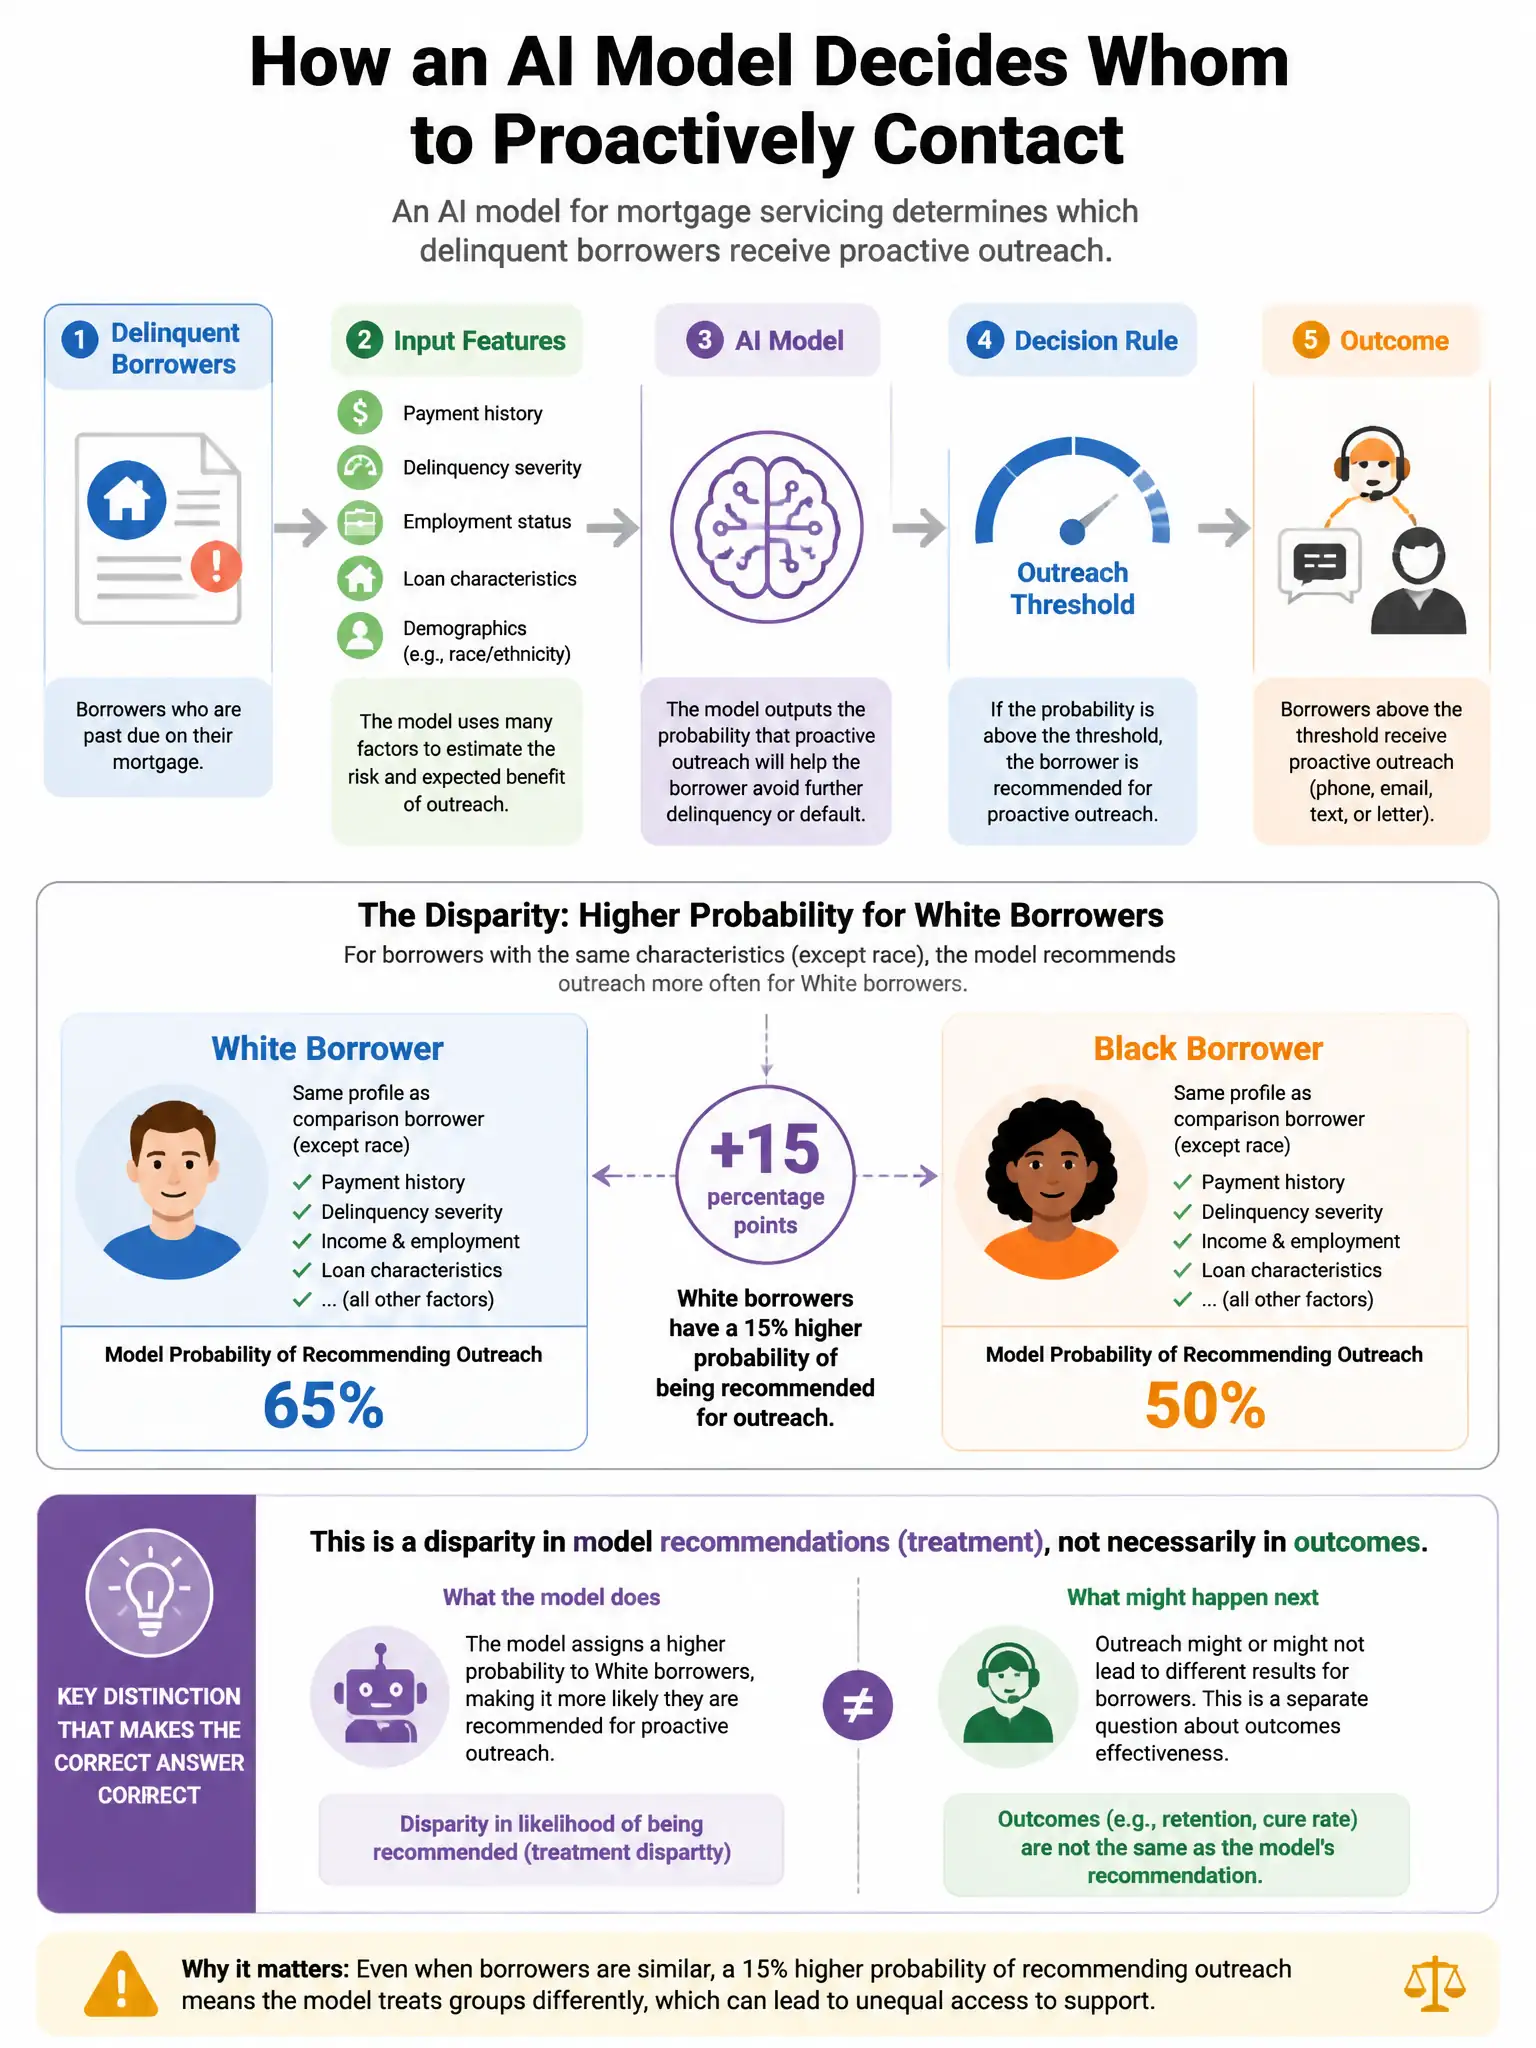
An AI model for mortgage servicing determines which delinquent borrowers receive proactive outreach. The model has a 15% higher probability of recommending outreach for White borrowers than Black borrowers with identical financial profiles. Under which framework is this MOST likely a violation?
Select an answer to reveal the explanation.
Short Explanation
Here's the deal — you're looking at a fair lending violation because ECOA and CFPB guidance cover all parts of credit, including servicing and loss-mitigation outreach. If the model gives proactive help to White borrowers but not equally qualified Black borrowers, that's racial discrimination in credit-related services.
Full Explanation
CFPB fair lending guidance and ECOA are the correct framework because they prohibit discrimination in all aspects of credit transactions, including credit-related services such as loss-mitigation outreach, for discriminatory differences in credit-related services based on race. A model that systematically denies proactive assistance to Black borrowers with financial profiles equivalent to White borrowers who receive outreach constitutes racial discrimination in credit servicing. The NIST AI RMF GOVERN function option is wrong because it is a risk-management framework, not a legal violation. The GDPR Article 22 option is wrong because GDPR is a European regulation and Article 22 pertains to EU residents. The SEC Regulation Fair Disclosure option is wrong because it applies to material nonpublic information to investors, not consumer financial services.