
A derivatives-informed equity PM observes that a stock's 30-day implied volatility (IV) is trading at a 40% premium to its 90-day realized volatility (RV) in the weeks preceding an earnings announcement. An AI system flags this divergence as a potential signal. Which interpretation of this IV/RV spread is MOST consistent with options market microstructure theory, and what is the appropriate equity-level trade expression?
Select an answer to reveal the explanation.
Short Explanation
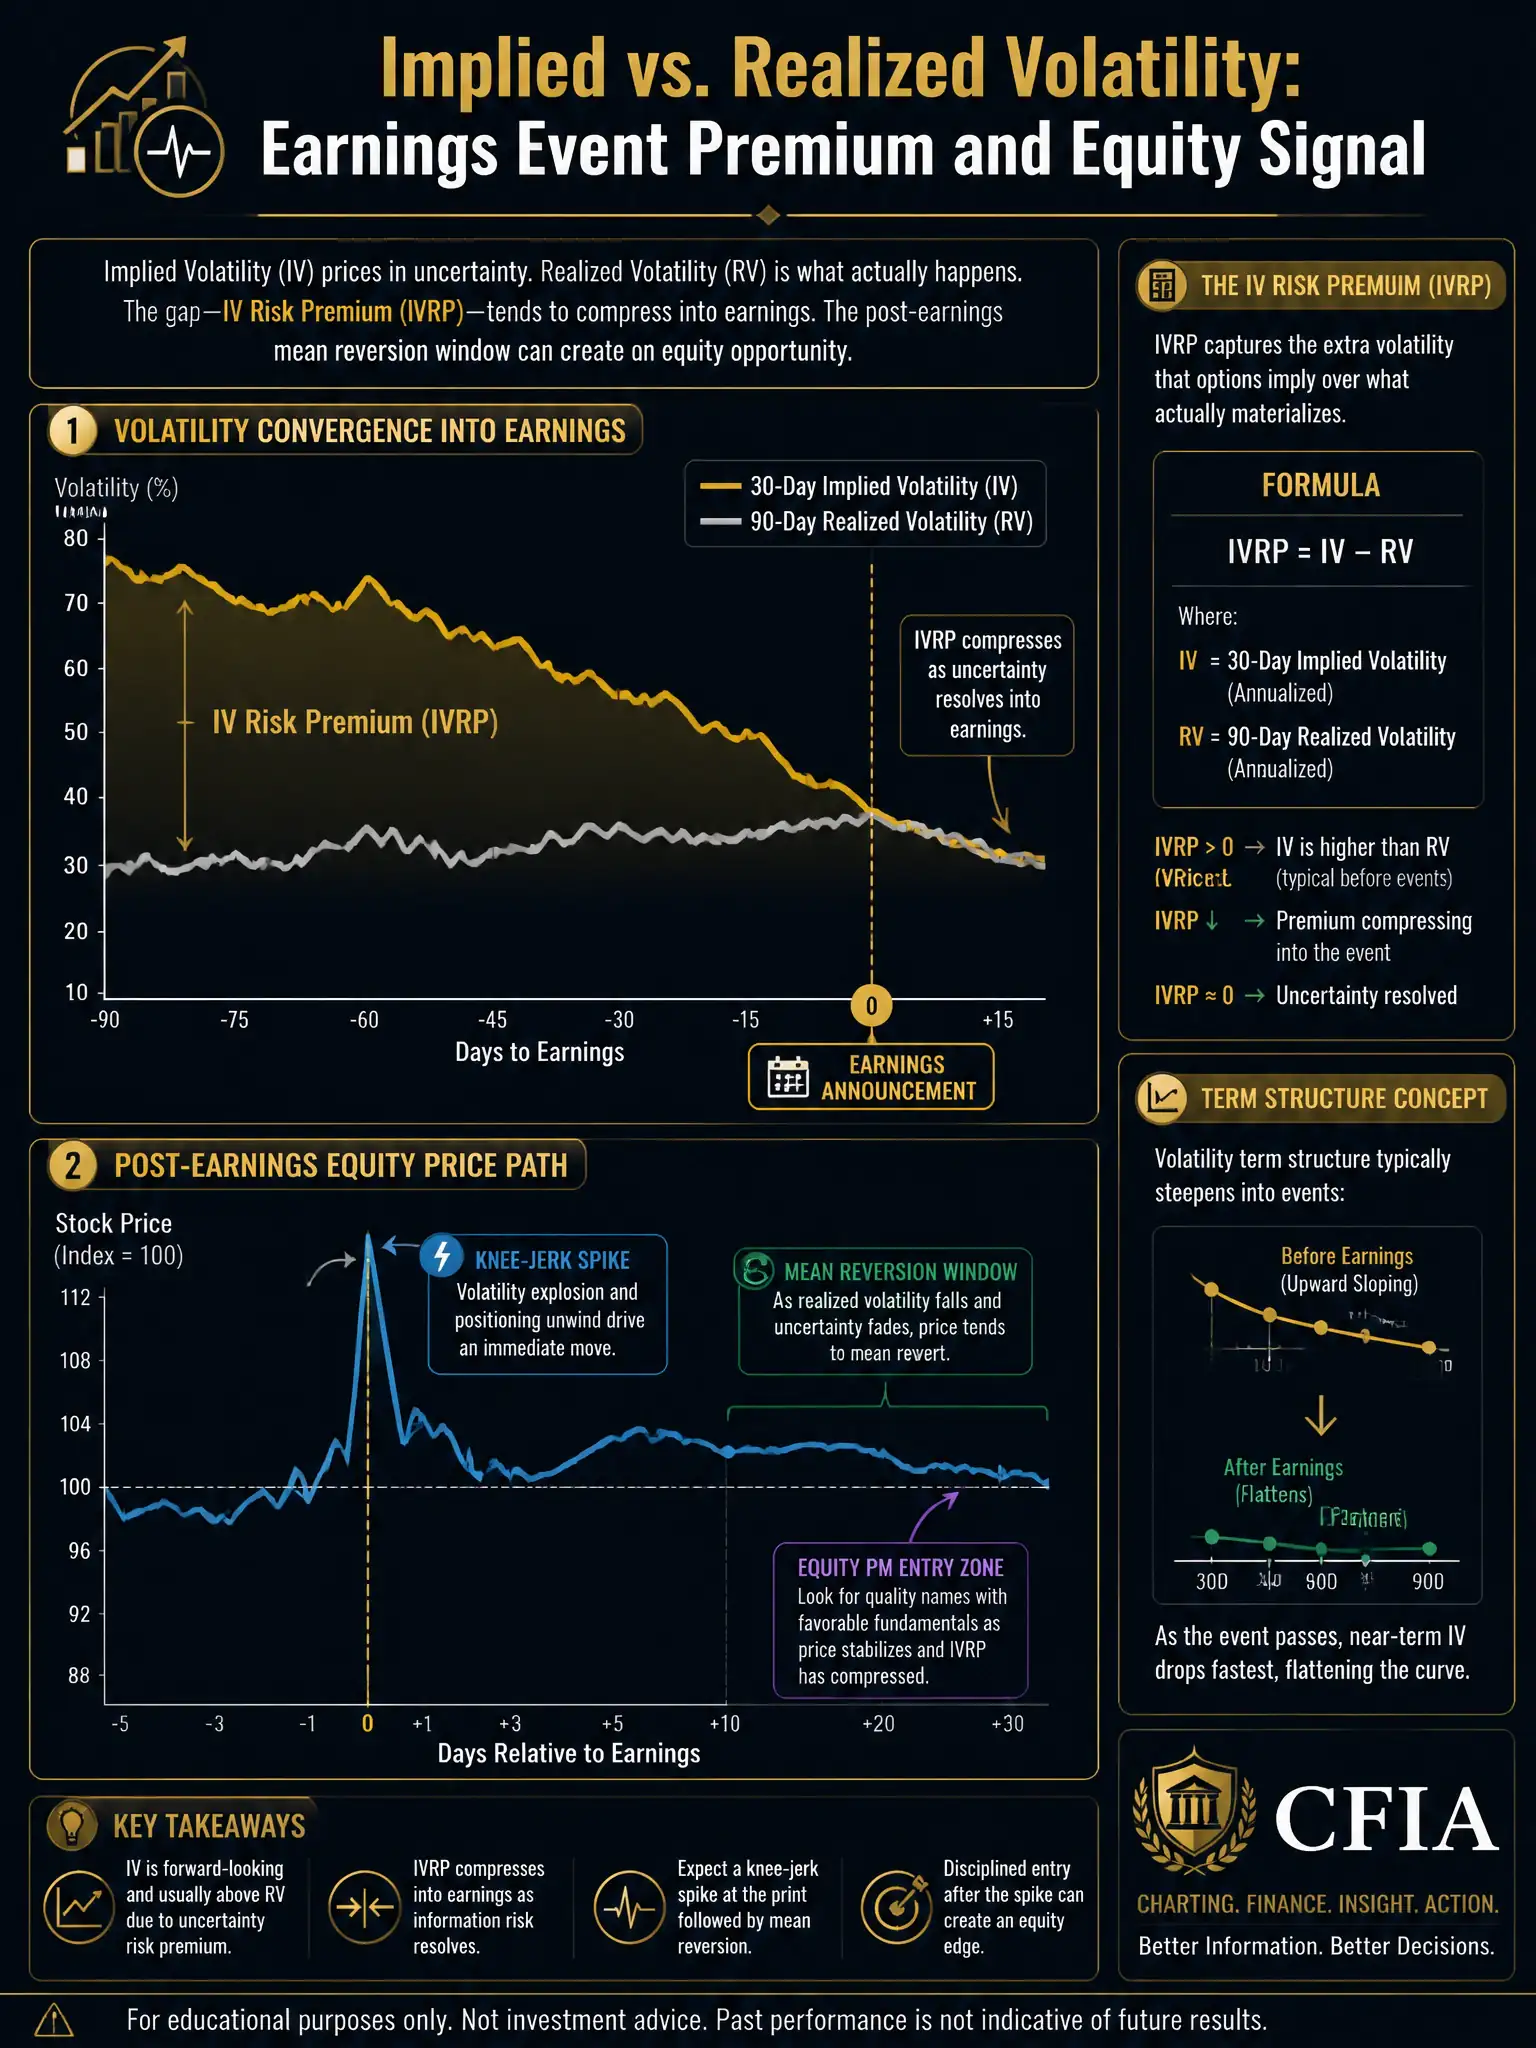
When implied volatility is way above realized volatility before earnings, the crowd is usually overpaying for event insurance. You shouldn't assume that means the stock will make a huge move; it often means the move gets overpriced and reverts after the announcement.
Full Explanation
The correct interpretation is that the IV/RV spread reflects a volatility risk premium elevated by event uncertainty, and the equity-level implication is that market consensus expects a large move but may overestimate its magnitude, creating opportunity in a mean-reversion overlay after the announcement. The IV/RV spread captures the implied volatility risk premium (IVRP) — the systematic tendency for option-implied volatility to exceed subsequent realized volatility, particularly around earnings announcements. This premium compensates option sellers for bearing event uncertainty and jump risk. Academic work by Carr and Wu (2009) and Bollerslev, Gibson, and Zhou (2011) documents this premium as a persistent, systematic feature of equity option markets. For an equity-level PM who does not trade options directly, the IVRP carries informational content about consensus expectations. When IV is significantly elevated versus RV, the market is pricing in a large move. If the announcement resolves without an extreme outcome, the stock tends to exhibit mean-reverting behavior — the initial knee-jerk reaction often overshoots fair value in both directions before settling. Disciplined equity PMs can exploit this by waiting for the post-announcement volatility to spike and then entering a position in the direction consistent with fundamental analysis, with a shorter holding period that captures the reversion to fair value. Additionally, the term structure of implied volatility — specifically the 30-day vs. 90-day IV comparison — provides information about where the market is concentrating its uncertainty. Sharp kinks in the term structure at near-term expiration dates are calendar-pinning signals that event-driven positioning is dominant in short-dated options. The interpretation that elevated IV indicates institutional accumulation of the underlying stock in anticipation of a positive earnings surprise, with a trade to buy the stock outright at current prices, incorrectly conflates directional options positioning with IV levels. High IV can be driven by both put and call buying — elevated IV without skew analysis provides no directional inference about institutional positioning. The interpretation that high IV relative to RV universally signals bearish institutional positioning, with a trade to initiate a short position in the equity and hold through the announcement, makes the same logical error in the bearish direction. The interpretation that the divergence is a data artifact caused by the term structure of options liquidity and has no predictive value for either the equity or volatility surface is incorrect; decades of empirical evidence and the entire volatility arbitrage industry contradict the claim that IV/RV divergences carry no predictive content.