
An investment advisory firm deploys an AI system that generates individualized stock recommendations delivered via a mobile app to retail clients. The firm's legal team argues that because no human reviews individual recommendations before delivery, the firm avoids the definition of 'investment adviser' under the Investment Advisers Act of 1940 and has no disclosure obligations. Which assessment is most accurate?
Select an answer to reveal the explanation.
Short Explanation
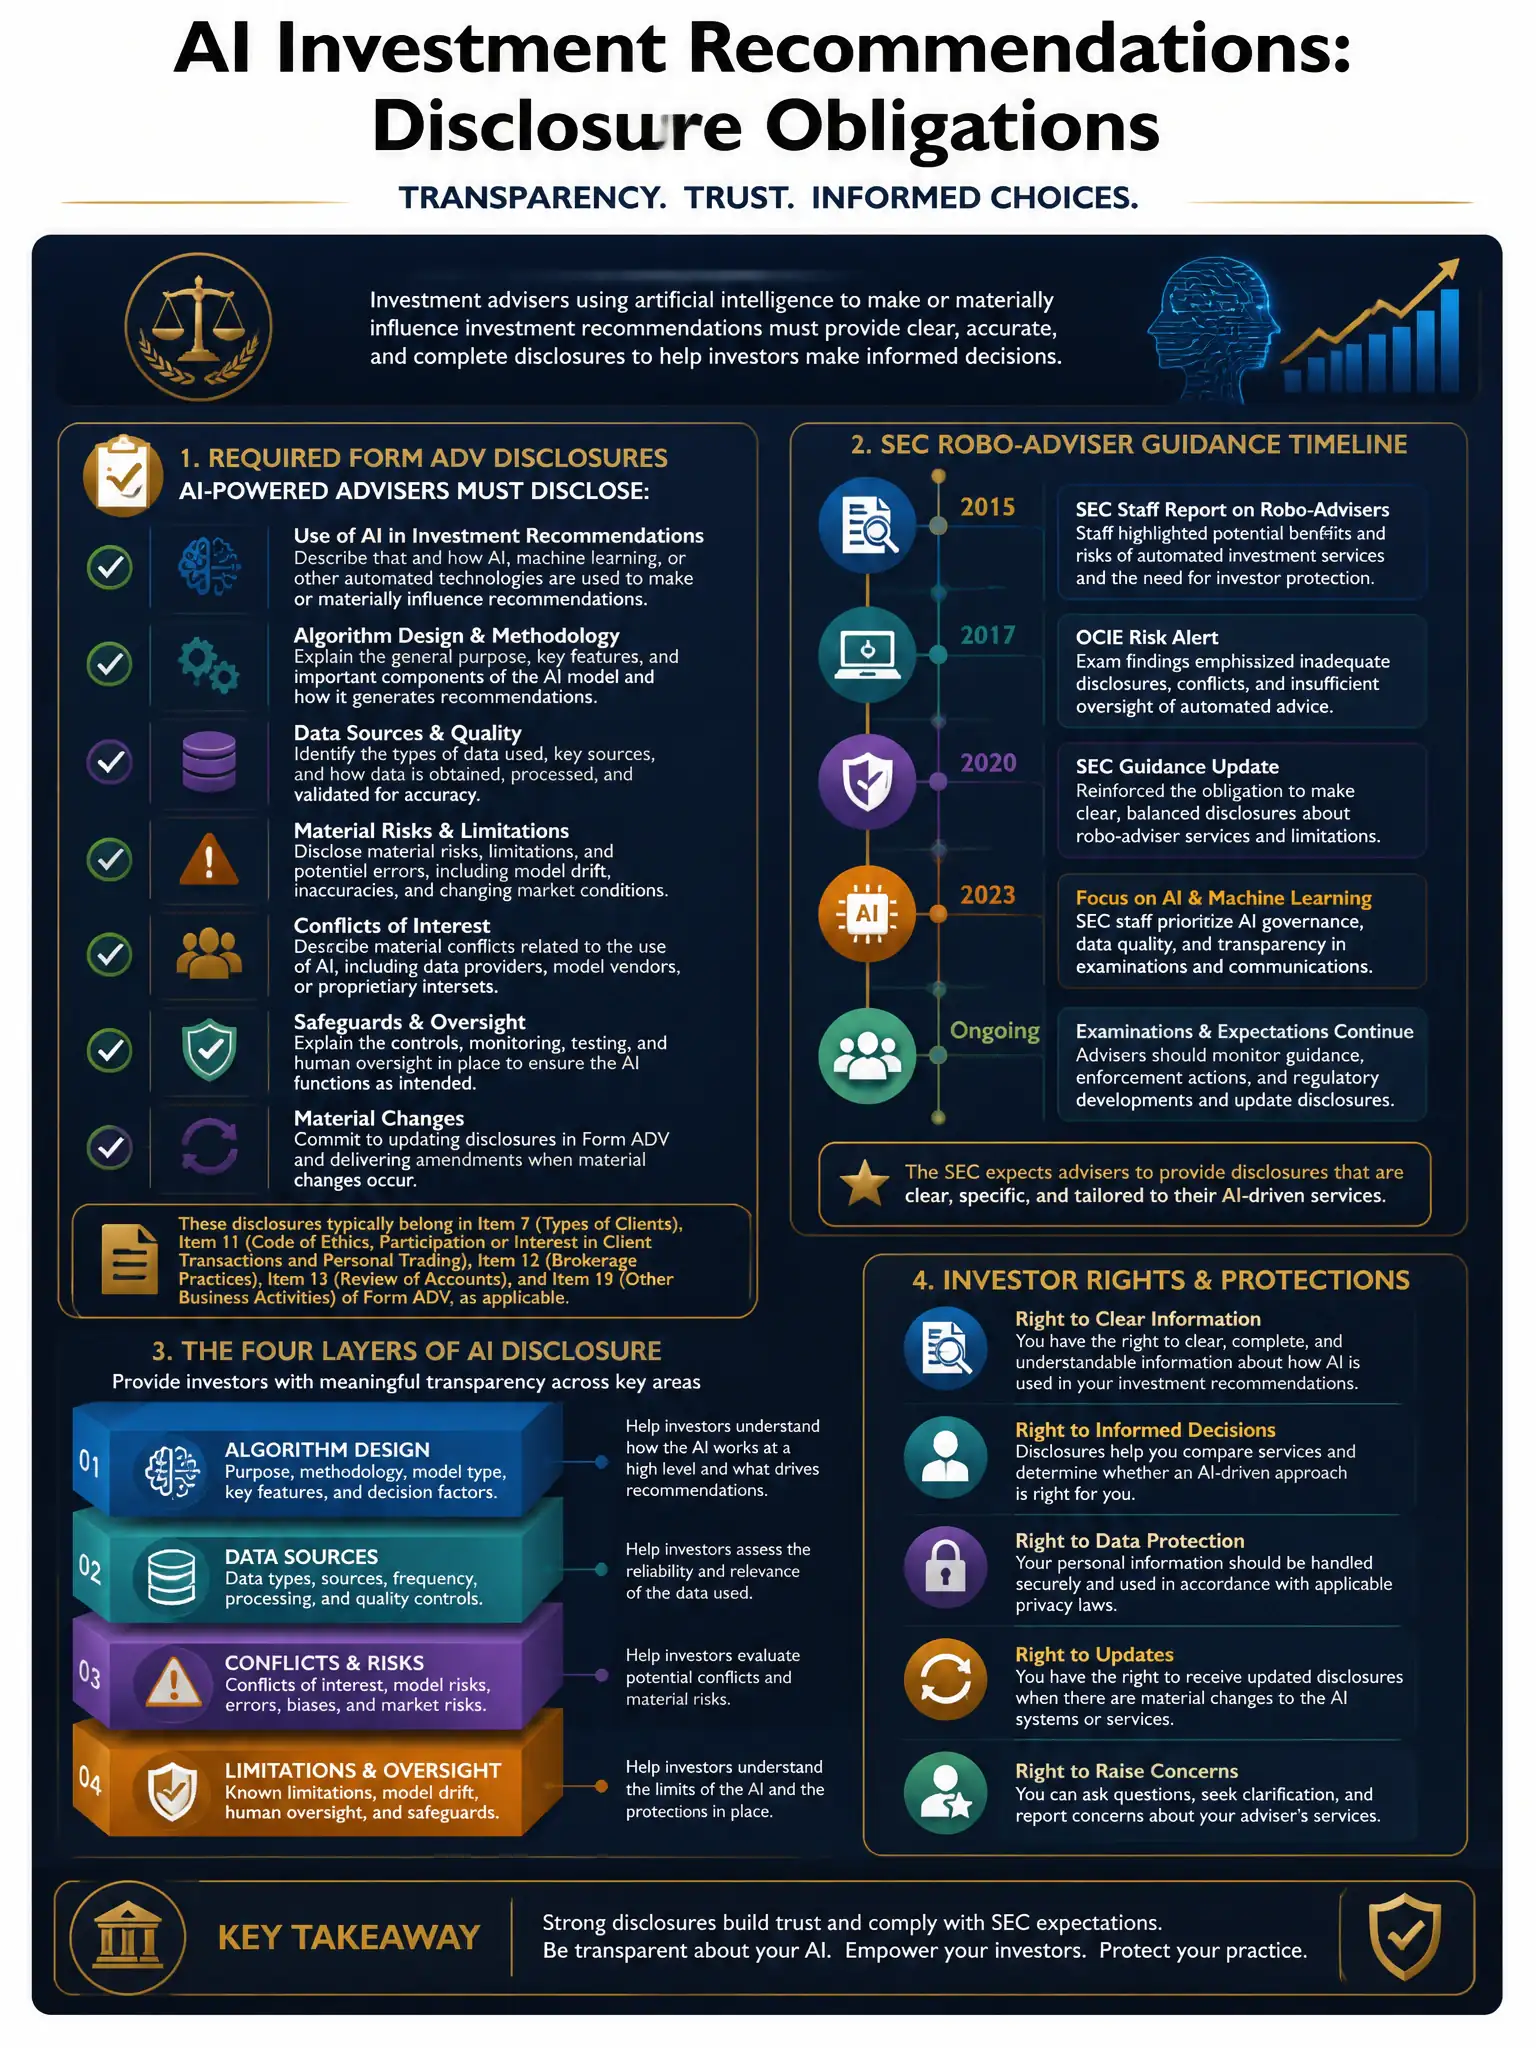
The SEC settled this question years ago with robo-advisory guidance: if you're in the business of giving individualized investment advice for compensation, you're an investment adviser — full stop. Automation doesn't change the registration trigger. You must disclose the AI's role, training data, conflicts, and material limitations, and one-time consent isn't a substitute for ongoing Form ADV disclosure.
Full Explanation
The Investment Advisers Act of 1940 defines an investment adviser as any person who 'for compensation, engages in the business of advising others...as to the value of securities or as to the advisability of investing in, purchasing, or selling securities.' The SEC and courts have consistently interpreted 'person' to include entities operating through automated means — the mechanism of delivery does not change the legal character of the activity.
The SEC's 2017 and 2023 guidance on robo-advisers explicitly affirmed that automated investment advisory platforms are subject to the same fiduciary obligations, registration requirements, and disclosure mandates as human advisers. Critically, the SEC identified specific disclosure obligations unique to AI-powered advisory services: (1) the degree of human oversight, or lack thereof; (2) the basis on which the algorithm generates recommendations, including data sources and key assumptions; (3) conflicts of interest embedded in the model's design or training data (e.g., if the model favors products in which the firm has a revenue interest); and (4) material limitations of the automated methodology. Therefore, the firm is an investment adviser regardless of automation level and must disclose AI involvement in recommendations, conflicts of interest in the AI's design, and material limitations of the system in its Form ADV and client agreements.
The claim that automated systems without human review fall outside the Investment Advisers Act's scope, and that no disclosure is required, has been explicitly rejected by the SEC in enforcement contexts. The view that the firm must register only if assets under advisement exceed the SEC threshold, and that below that threshold AI-generated recommendations are unregulated, confuses the assets-under-advisement threshold for SEC versus state registration with the question of whether registration is required at all. The threshold determines which regulator, not whether regulation applies. The view that the firm must obtain explicit client consent to AI-generated recommendations but has no ongoing disclosure obligation once consent is obtained mischaracterizes the nature of disclosure obligations: Form ADV disclosures are ongoing and must be updated materially as the AI system changes, not satisfied by a one-time consent capture.
The 2023 SEC AI conflicts of interest rulemaking further requires advisers to eliminate or neutralize conflicts of interest in predictive data analytics tools, imposing affirmative obligations beyond mere disclosure. Firms using AI in client-facing investment advice should conduct a comprehensive regulatory mapping exercise covering Investment Advisers Act registration, Form ADV Part 2 disclosures, Regulation Best Interest for broker-dealer adjacent activities, and applicable state requirements.