
A robo-advisory platform uses a deep neural network to generate personalized portfolio recommendations for retail investors. The compliance team is designing the investor-facing disclosure. Which explainability approach best satisfies both regulatory expectations under MiFID II suitability rules and practical retail investor comprehension?
Select an answer to reveal the explanation.
Short Explanation
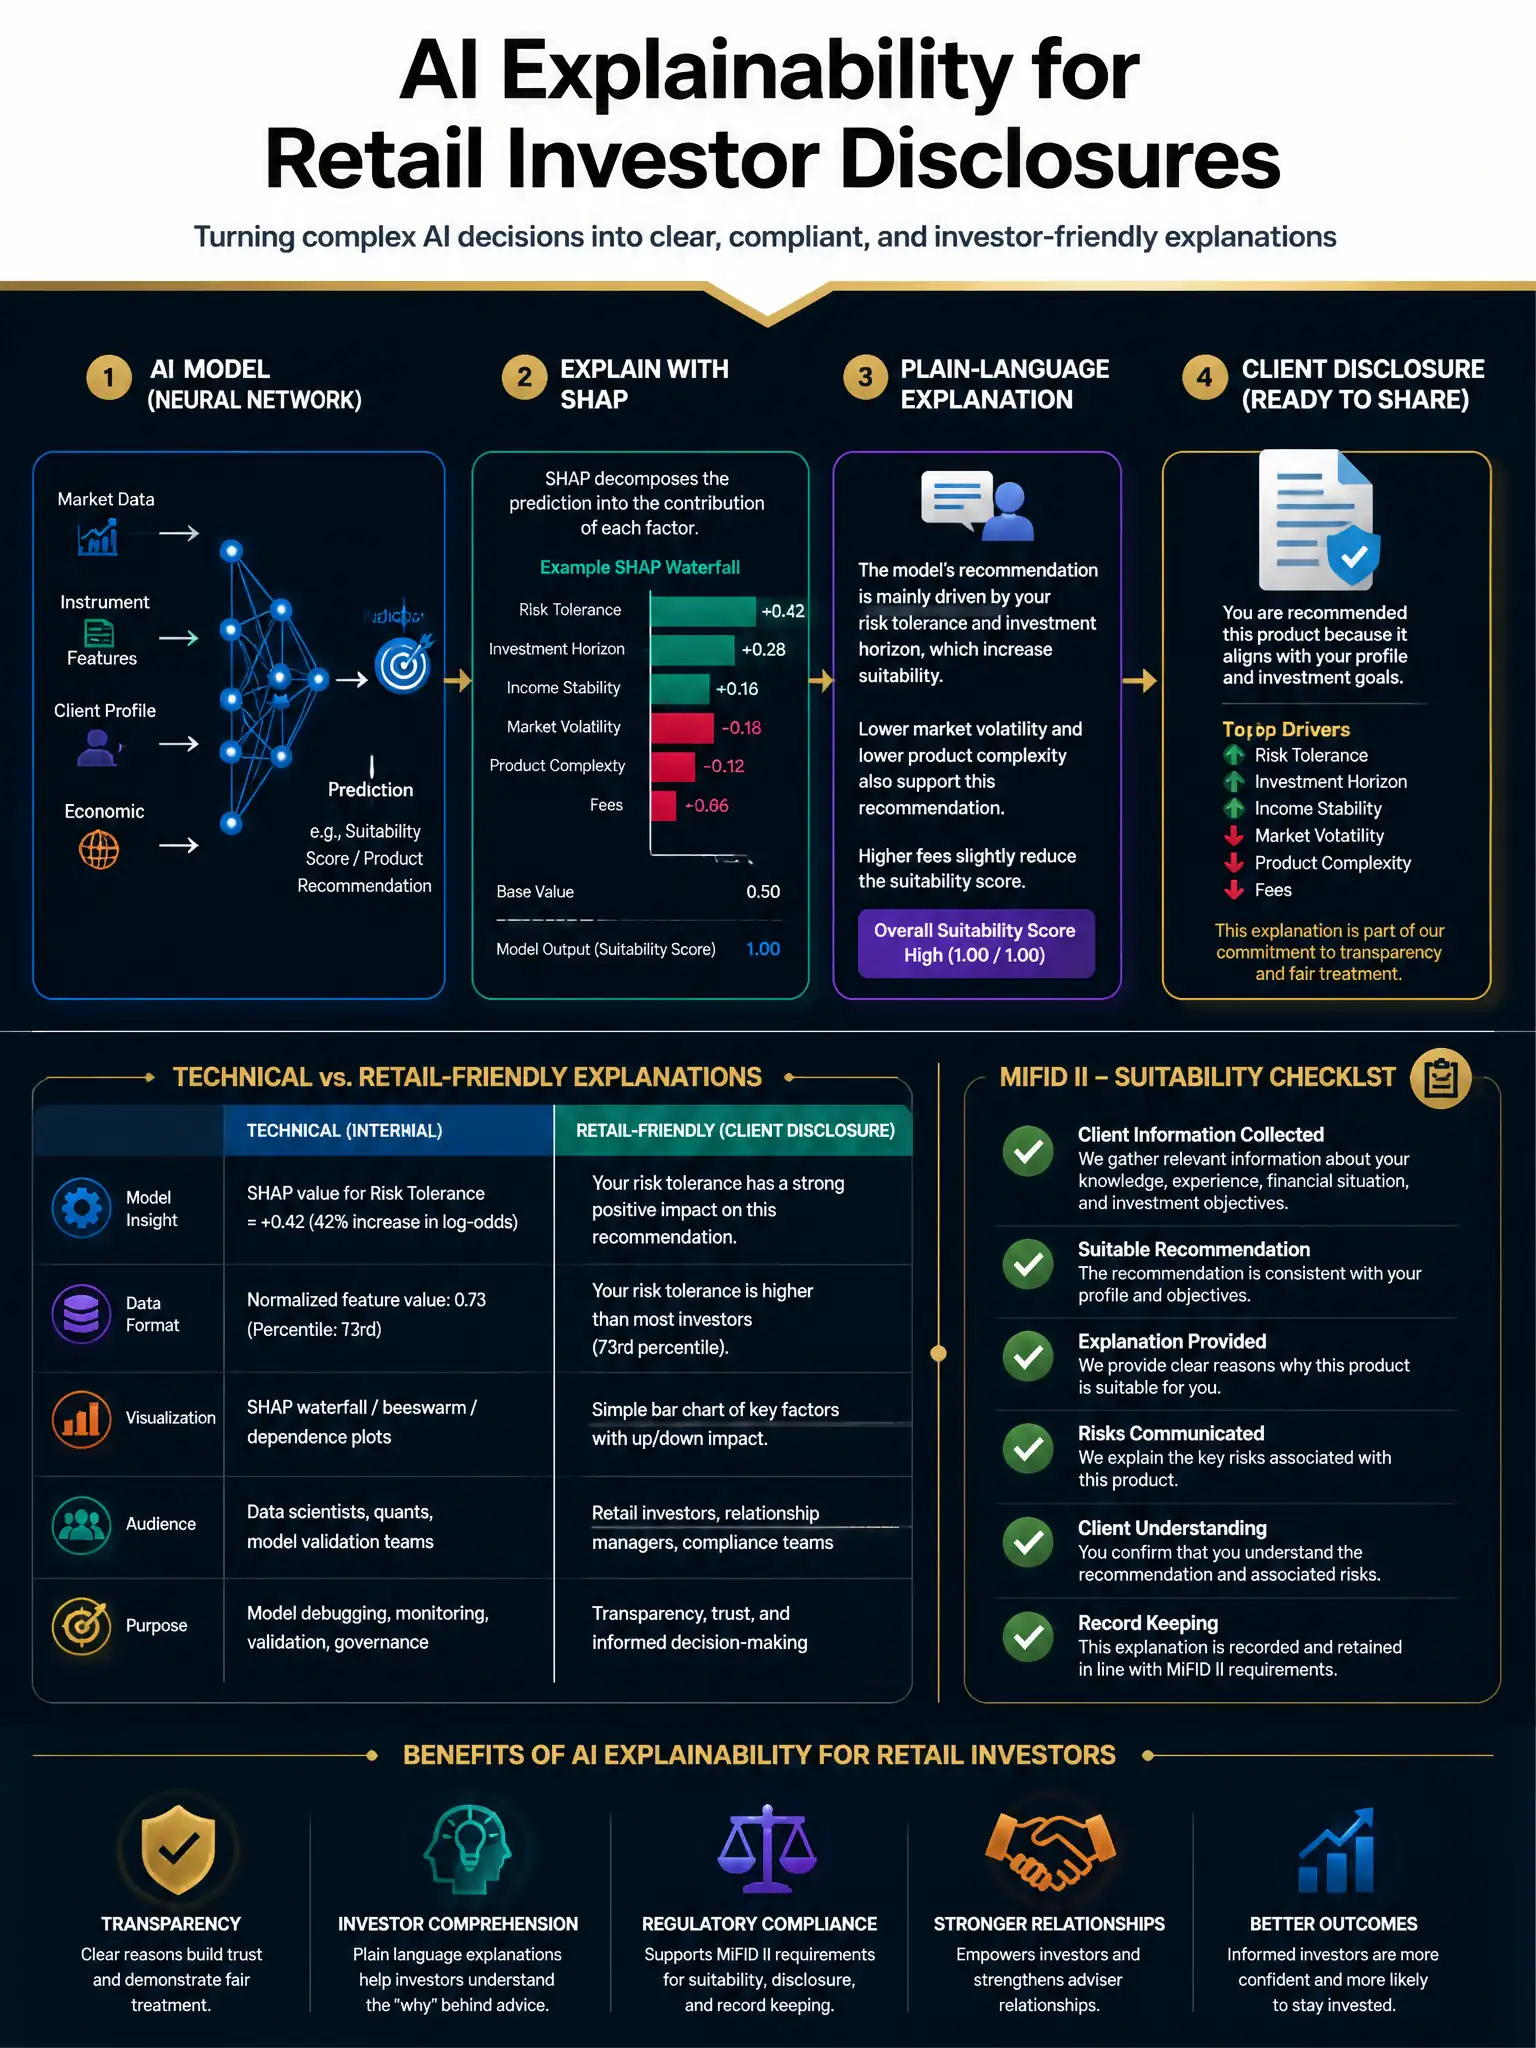
SHAP-based factor attribution shows you which client characteristics most influenced the recommendation, then translates them into plain language. That's what MiFID II suitability really needs: a reason the investor can evaluate, not a math lecture.
Full Explanation
MiFID II Article 25 and the associated ESMA suitability guidelines require investment firms to explain why a recommendation is suitable for the specific client, referencing the client's financial situation, investment objectives, and risk tolerance. The obligation is substantive — a generic disclosure that 'an algorithm was used' does not satisfy the requirement to explain the basis for suitability.
For neural networks and other non-interpretable models, post-hoc explainability methods like SHAP (SHapley Additive exPlanations), LIME (Local Interpretable Model-Agnostic Explanations), or integrated gradients produce local feature attributions: quantified estimates of how much each input feature contributed to a specific output for a specific client. These outputs can be ranked and translated into natural language — for example, 'Your recommendation for a balanced fund was primarily driven by your moderate risk score (40%), followed by your 10-year investment horizon (35%) and existing cash holdings (25%).'
Publishing the model's full weight matrices and activation functions is both technically meaningless to retail investors and potentially a proprietary information disclosure issue. It inverts the purpose of explainability — transparency to the client, not technical reproducibility for experts. Stating that the recommendation is algorithmically generated and directing investors to the firm's model risk policy document fails the retail comprehension standard; ESMA guidance explicitly requires explanations that are understandable to the target client segment. Disclosing only the asset classes recommended without referencing AI involvement omits AI disclosure entirely, which increasingly conflicts with both MiFID II suitability rules and emerging AI-specific disclosure frameworks including the EU AI Act's transparency obligations for high-risk systems.
Architecturally, the best practice is a two-layer disclosure: a plain-language investor-facing summary (the SHAP-derived narrative) and a more detailed technical explanation available on request for more sophisticated clients. This layered approach satisfies regulatory expectations while respecting retail investors' actual information needs.