
A quantitative fund is building an ML system to extract directional signals from real-time options order flow. The system must distinguish informed trading from hedging activity to generate actionable equity signals. Which feature engineering approach most effectively isolates informed options flow?
Select an answer to reveal the explanation.
Short Explanation
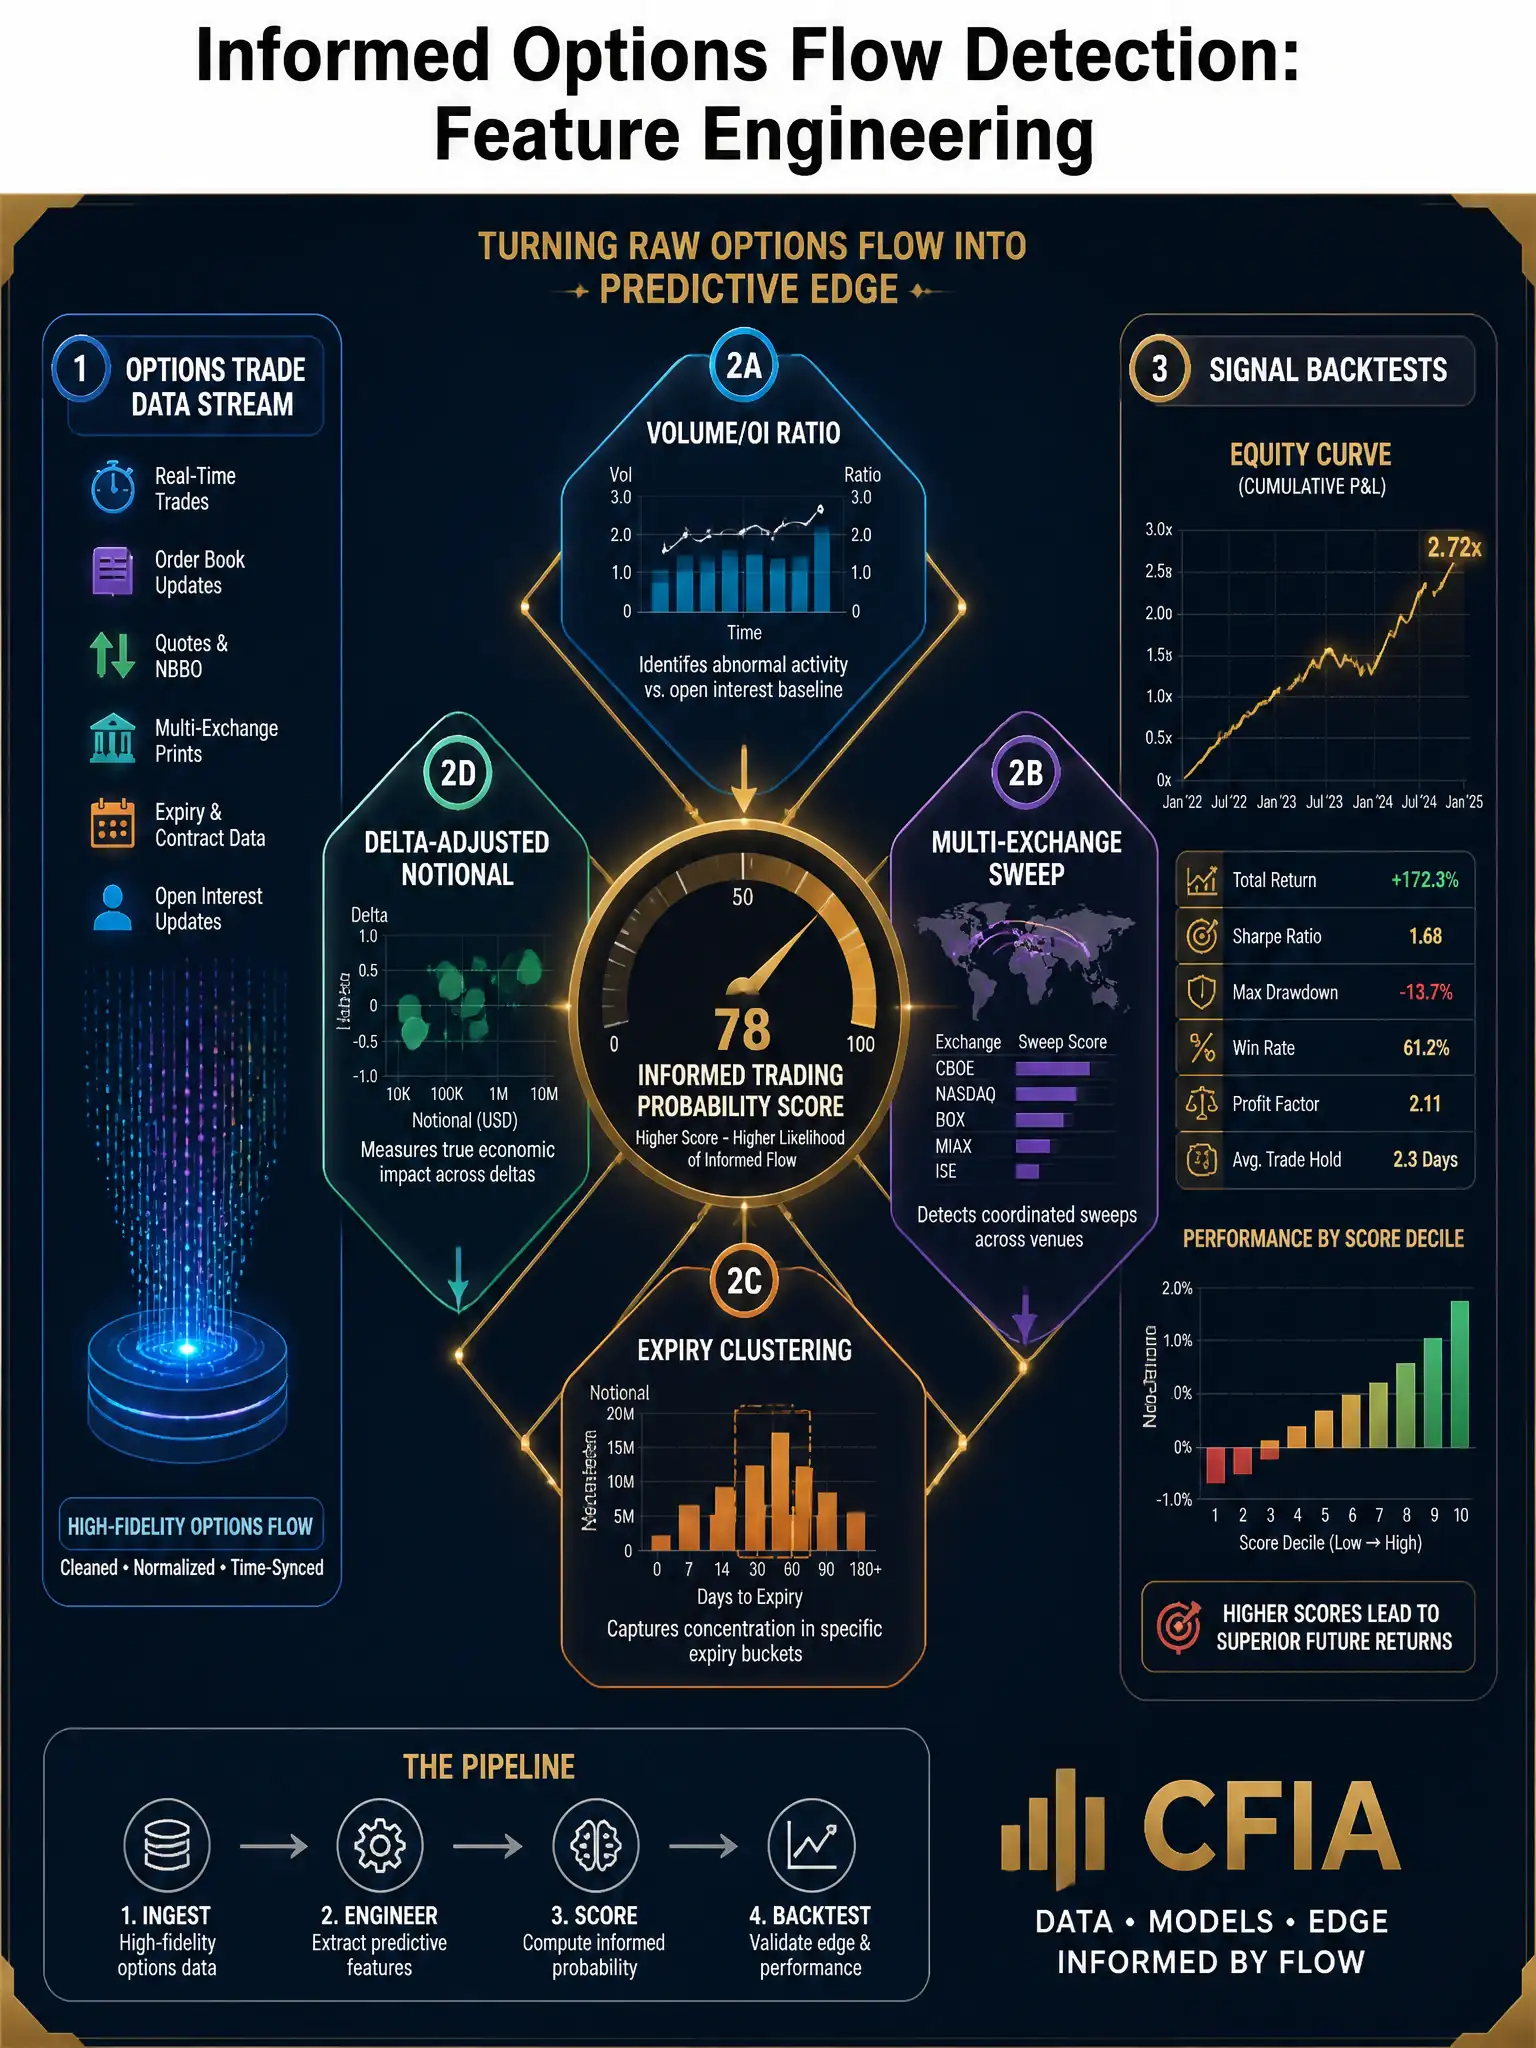
Options flow is like a crowded room: most of the noise is hedging, market-making, and retail speculation. You can't just watch volume or sentiment; you isolate informed traders by combining tells like sweeps across exchanges, expiry clustering, unusual volume against open interest, and delta-adjusted size into one probability score.
Full Explanation
Options market microstructure research (Easley, O'Hara, and Srinivas; Pan and Poteshman) consistently demonstrates that informed traders prefer options over equities because options provide leverage, limited downside risk, and a degree of anonymity. Detecting informed flow is therefore a signal extraction problem: the majority of options activity reflects market-making, retail speculation, and portfolio hedging, and the fund must isolate the minority that reflects genuine directional information. The multi-factor informed-trading probability score approach is correct because it combines unusual volume relative to open interest, sweep orders crossing multiple exchanges, time-to-expiry clustering, and delta-adjusted notional size. Volume-to-open-interest ratio identifies contracts being newly initiated, meaning high volume on low open interest, rather than liquidated. Sweep orders crossing multiple exchanges in milliseconds indicate institutional urgency. Expiry clustering near specific dates, such as earnings, FDA decisions, or known catalysts, links the position to a specific informational event. Delta-adjusted notional size filters out small retail trades. ML models trained on these features, particularly gradient boosting architectures given the tabular data structure, have demonstrated statistically significant Sharpe ratios in out-of-sample testing at institutions including Citadel and Jane Street. The total open interest daily threshold approach is wrong because it is a blunt instrument that captures high-hedging periods, such as around major index rebalances or FOMC meetings, as frequently as informed positioning, and open interest accumulation and composition are not equivalent signals. The deep in-the-money options approach is wrong because it is counterproductive for detecting informed traders. ITM options are typically purchased by investors seeking leveraged delta exposure with low time-premium risk, a relatively common hedging and income strategy. Informed traders more often use slightly out-of-the-money options where the cost basis is low and the asymmetric payoff is highest if their directional thesis is correct. The put/call ratio approach is wrong because the put/call ratio is a well-known and broadly followed sentiment indicator, so it is largely arbitraged by the time it reaches a threshold signal level, and academic research consistently finds that simple put/call ratio strategies have near-zero alpha net of transaction costs in modern markets.