
A European bank uses three separate AI systems: (1) a real-time credit scoring model that determines loan eligibility for retail customers, (2) a customer service chatbot that answers FAQ-type questions on the bank's mobile app, and (3) a social credit scoring system that rates customer trustworthiness based on social media behavior for access to financial products. Under the EU AI Act (Regulation 2024/1689), how should these three systems be classified?
Select an answer to reveal the explanation.
Short Explanation
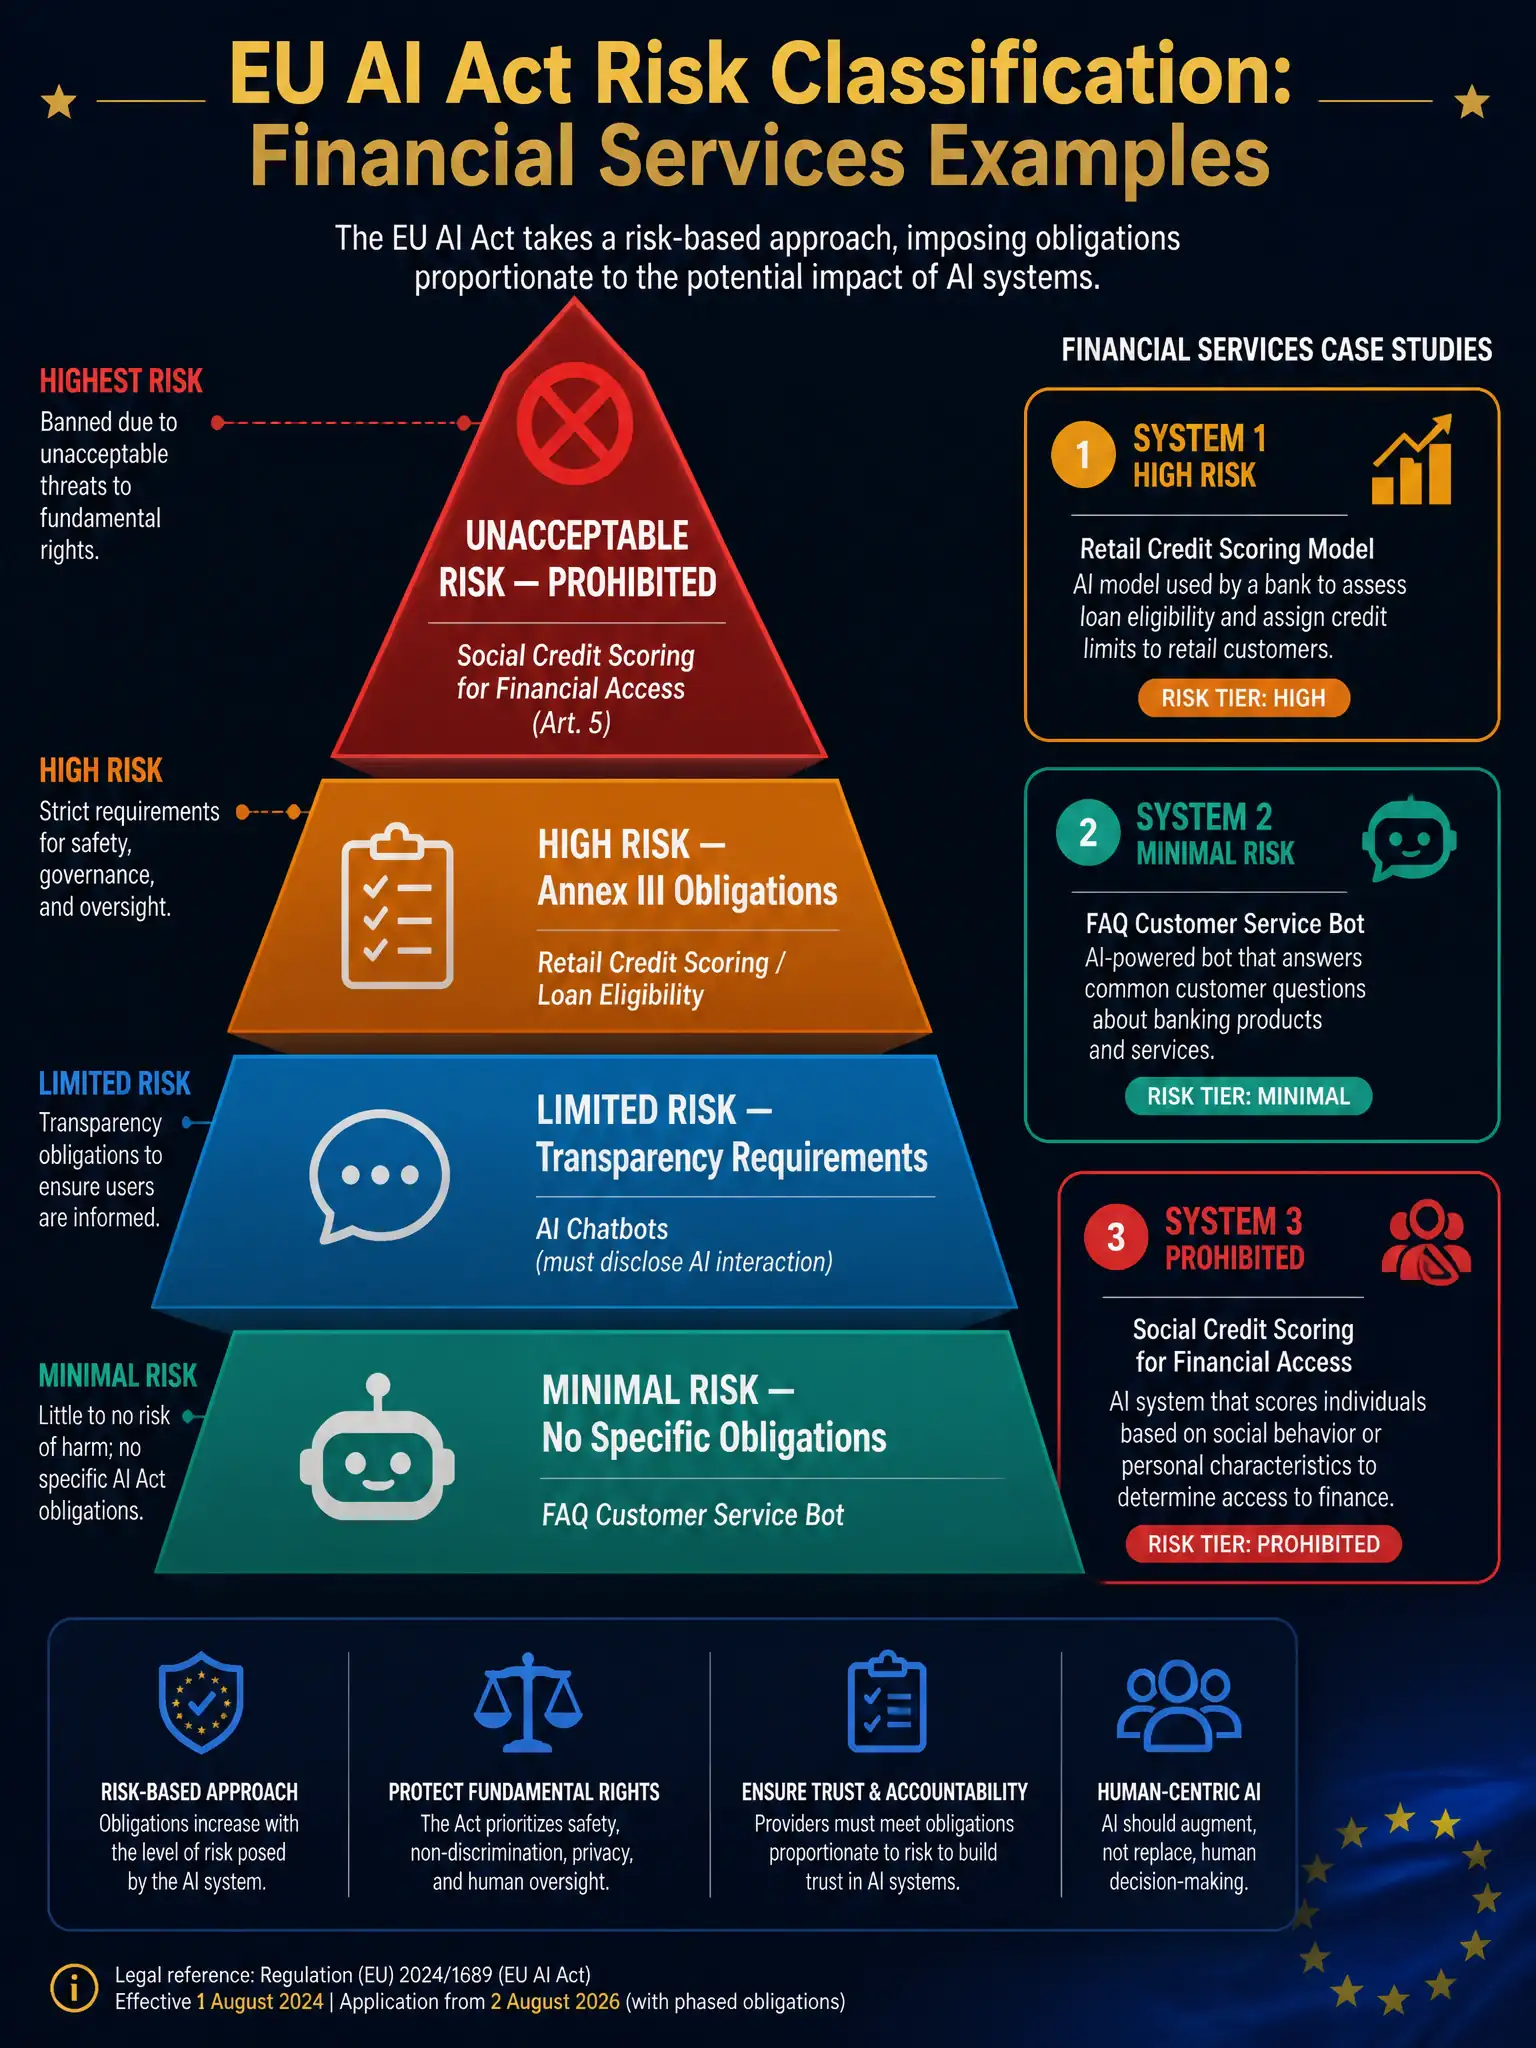
You classify by use case, not by who deploys it. Social credit scoring based on social behavior to restrict financial access is banned, credit scoring for loan eligibility is High-Risk, and a basic FAQ chatbot is Minimal-Risk. Think of it as a traffic light with an extra color for things so dangerous they're just banned.
Full Explanation
The EU AI Act (Regulation 2024/1689, entering into force August 2024) establishes a four-tier risk classification system: Unacceptable Risk (prohibited), High Risk, Limited Risk, and Minimal Risk. Classification is determined by the AI system's use case and potential for harm, not by the regulated status of the deploying organization. The correct classification is the credit scoring model as High-Risk, the FAQ chatbot as Minimal-Risk, and the social credit scoring system as Unacceptable-Risk.
The credit scoring model is High-Risk because Annex III of the EU AI Act explicitly lists 'AI systems used to evaluate the creditworthiness of natural persons or establish their credit score' as High-Risk AI. High-Risk AI systems must comply with mandatory requirements including data governance, technical documentation, transparency, human oversight, accuracy/robustness standards, and registration in the EU AI database. This classification applies regardless of the model's architecture (traditional ML, deep learning, etc.).
The FAQ chatbot is Minimal-Risk because a simple customer service chatbot that answers pre-defined questions about products and services, without making consequential decisions, falls into the Minimal Risk tier. The only additional obligation that might apply is Limited Risk transparency (disclosing to users that they are interacting with an AI) under Article 52—but a straightforward FAQ bot with no deceptive intent would not trigger even Limited Risk classification. The correct classification treats this as Minimal Risk.
The social credit scoring system is Unacceptable-Risk because Article 5 of the EU AI Act explicitly prohibits AI systems that evaluate or classify individuals based on their social behavior or personal characteristics in ways that lead to detrimental or unfavorable treatment in contexts unrelated to those in which the data was generated. Using social media behavioral data to generate a 'trustworthiness' score that restricts access to financial products is a paradigmatic example of prohibited social scoring, regardless of whether the deploying entity calls it a 'credit risk model.' This system is Unacceptable Risk and must not be deployed.
The claim that all three systems are High-Risk because they're used by a regulated financial institution is incorrect because the EU AI Act classifies by use case, not by institutional status. A minimal-risk chatbot at a bank is still minimal risk.
The classification that makes the credit scoring model Unacceptable-Risk, the FAQ chatbot Limited-Risk, and the social credit scoring system High-Risk is incorrect. These are inverted—credit scoring for loan eligibility is High-Risk (not banned), while social scoring for financial access is explicitly prohibited.
The classification that makes the credit scoring model High-Risk, the FAQ chatbot Limited-Risk, and the social credit scoring system Minimal-Risk is incorrect. Social credit scoring is not merely regulated under High-Risk provisions; it is outright prohibited under Article 5. A straightforward FAQ chatbot also remains Minimal-Risk rather than Limited-Risk unless it triggers transparency obligations, which this basic FAQ use case does not.