
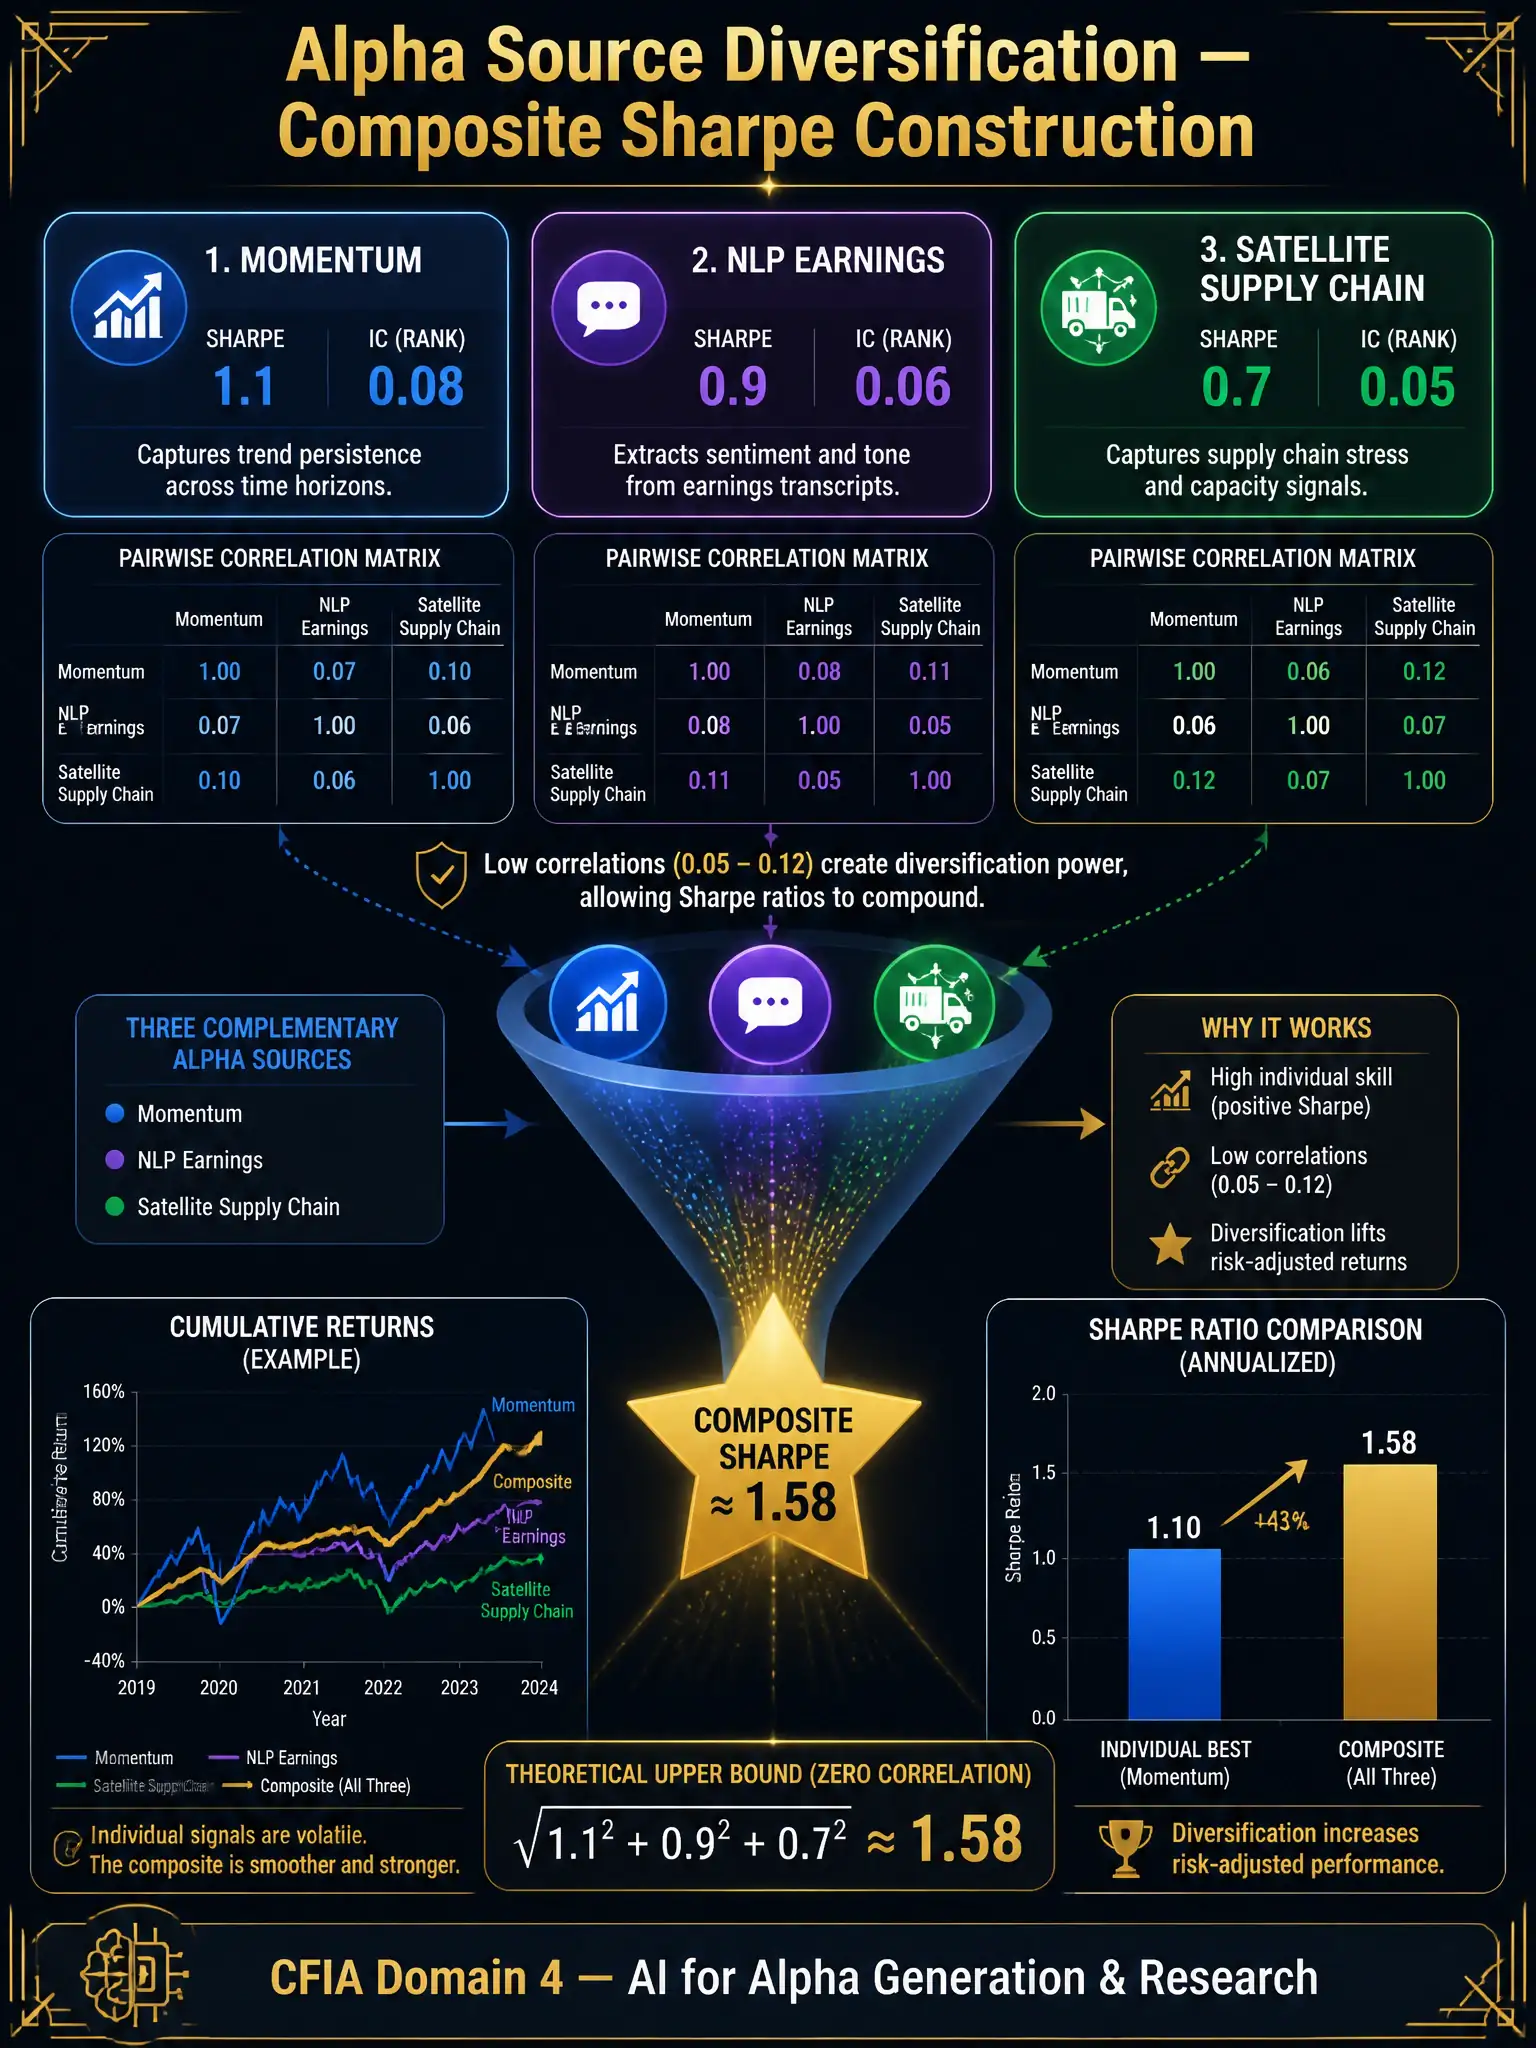
A systematic fund runs three alpha-generating models: (1) a momentum signal with IC of 0.08 and Sharpe of 1.1, (2) an NLP-based earnings sentiment signal with IC of 0.06 and Sharpe of 0.9, and (3) a satellite imagery-based supply chain signal with IC of 0.05 and Sharpe of 0.7. An analysis reveals the pairwise correlations between signal returns are: Momentum-NLP: 0.12, Momentum-Satellite: 0.05, NLP-Satellite: 0.08. What is the MOST important implication of the low inter-signal correlations for portfolio construction?
Select an answer to reveal the explanation.
Short Explanation
Diversification doesn't just apply to stocks—it applies to your alpha sources too. Three low-correlation signals are like three employees who rarely make mistakes at the same time, so combining them smooths bad days and lifts the composite Sharpe above any single signal.
Full Explanation
The core insight from modern portfolio theory applied to alpha construction is that the composite signal Sharpe ratio of uncorrelated or low-correlated signals is approximately equal to the square root of the sum of the squared individual Sharpe ratios, assuming equal weighting and zero inter-signal correlation. For the three signals described: sqrt(1.1 squared + 0.9 squared + 0.7 squared) is approximately sqrt(1.21 + 0.81 + 0.49), which is approximately sqrt(2.51), or about 1.58. Even if the realized pairwise correlations are slightly positive, from 0.05 to 0.12, the composite Sharpe would still materially exceed the best individual Sharpe of 1.1. The suggestion that weak correlations mean at least one signal is unreliable and should be removed misunderstands the role of low-IC signals in diversified composites. The satellite imagery signal with IC of 0.05 and Sharpe of 0.7 contributes meaningfully to the composite precisely because it is nearly uncorrelated with the other two signals, and removing it would reduce composite Sharpe. The recommendation to allocate the largest weight to the momentum signal because it has the highest individual Sharpe regardless of correlation is the traditional intuition that diversification corrects. In an uncorrelated environment, equal-weighting or optimal IC-weighted blending outperforms concentration in the best single signal because the highest-Sharpe signal has high variance in realized outcomes, which the other signals offset. The claim that low correlations indicate the signals are likely measuring the same underlying market phenomenon from different angles and will converge over time is incorrect. Low correlation between signals derived from momentum patterns, language understanding, and geospatial imagery reflects genuinely distinct information sources with different market microstructure exposures. They are not measuring the same phenomenon; the low correlation is a feature, not a warning sign. In practice, composite alpha construction at institutional systematic funds uses methods including equal risk contribution weighting, IC-weighted blending, and Markowitz optimization over signal returns to maximally exploit inter-signal diversification. The ongoing monitoring of pairwise correlations over rolling windows detects crowding events that can cause temporary correlation spikes.