
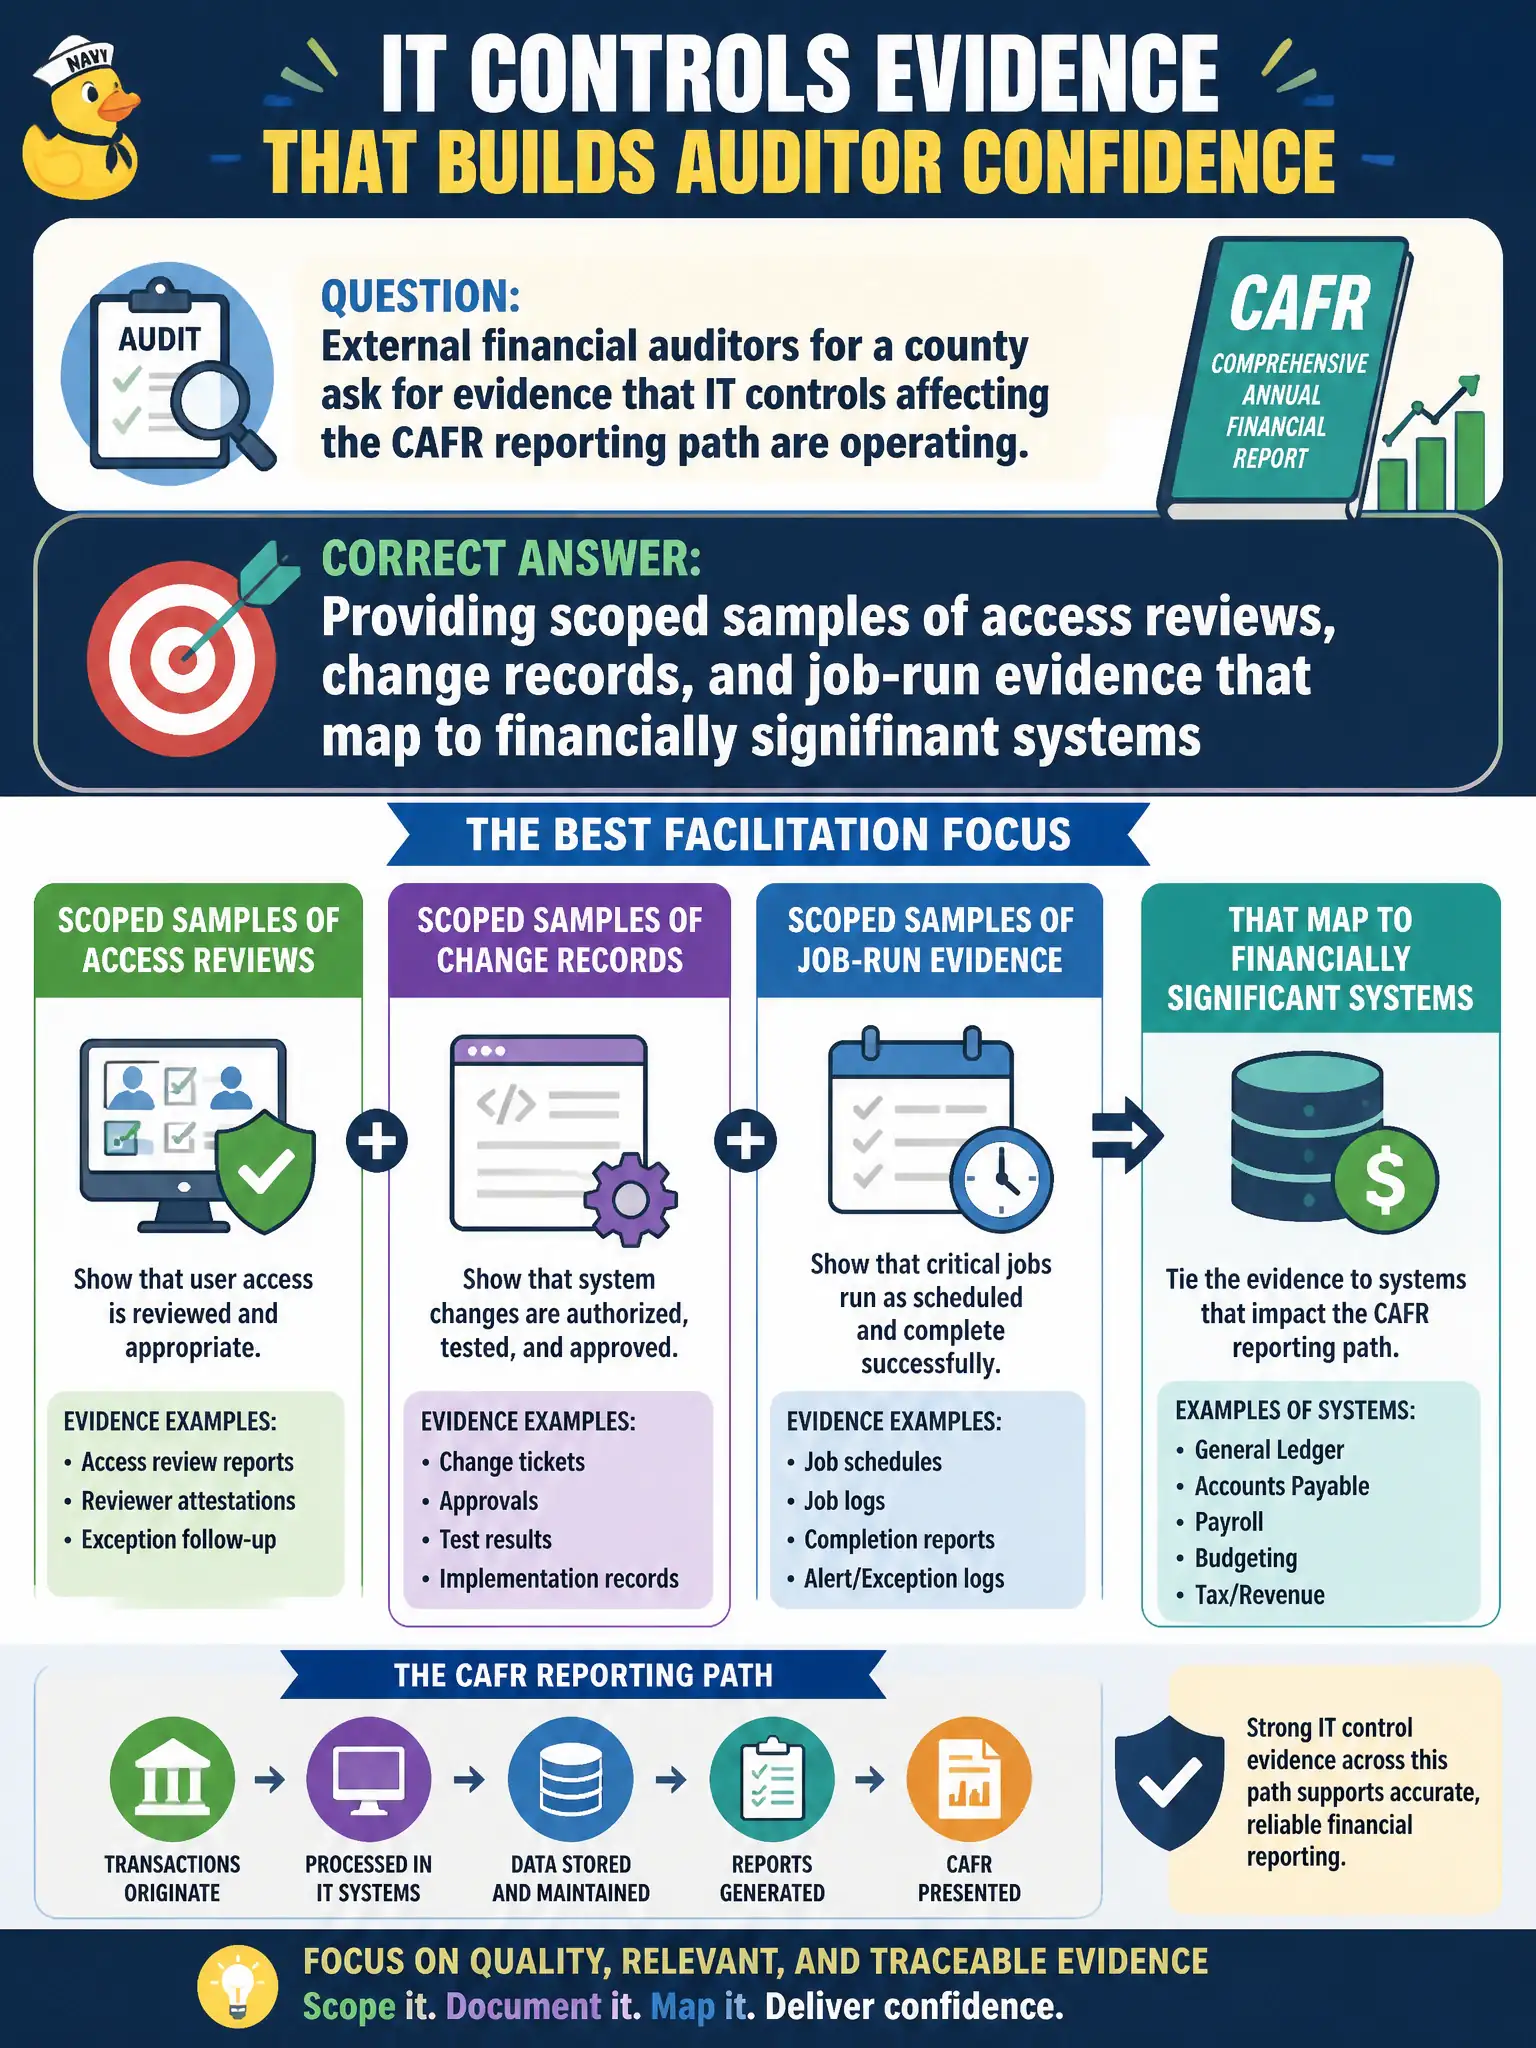
External financial auditors for a county ask for evidence that IT controls affecting the CAFR reporting path are operating. What is the security team's best facilitation focus?
Select an answer to reveal the explanation.
Short Explanation
Outside auditors are not there for a full red-team tour — they need proof that IT controls touching the books actually ran. Map access reviews, changes, and batch jobs to the financially significant systems and give clean samples. Dumping unrelated exploit kits or scrubbing logs just slows everyone down.
Full Explanation
External auditors examining a county’s financially significant systems need scoped, relevant evidence that IT controls supporting the financial statements actually operated—not a tour of every security tool in the environment. Useful samples typically include completed user access reviews for in-scope applications and supporting infrastructure, change records showing request, approval, testing, and production implementation for significant releases, and job-run or batch evidence for processes that post or interface into the general ledger. Mapping each sample to the systems and control objectives in the financial audit scope keeps the request proportional and defensible. Clear indexing, named control owners, and retention that covers the audit period reduce back-and-forth and demonstrate that evidence was maintained continuously rather than reconstructed under pressure.
Handing over every penetration-test exploit script without tying it to reporting objectives creates noise, may expose sensitive technique detail beyond need-to-know, and does not prove that access, change, or operations controls ran for the books. Replacing external auditors with the vulnerability scanner team collapses independence and confuses continuous technical testing with formal assurance over financial ITGCs. Deleting privileged-access logs to shrink review volume destroys the audit trail auditors must rely on and can itself become a finding or integrity concern. Exam caveat: scope and materiality drive what auditors ask for—breadth without relevance wastes both sides. Operationally, maintain a standing evidence binder (or equivalent repository) keyed to financially significant systems so access-review, change, and job samples can be exported quickly with hashes or exports that preserve integrity.