
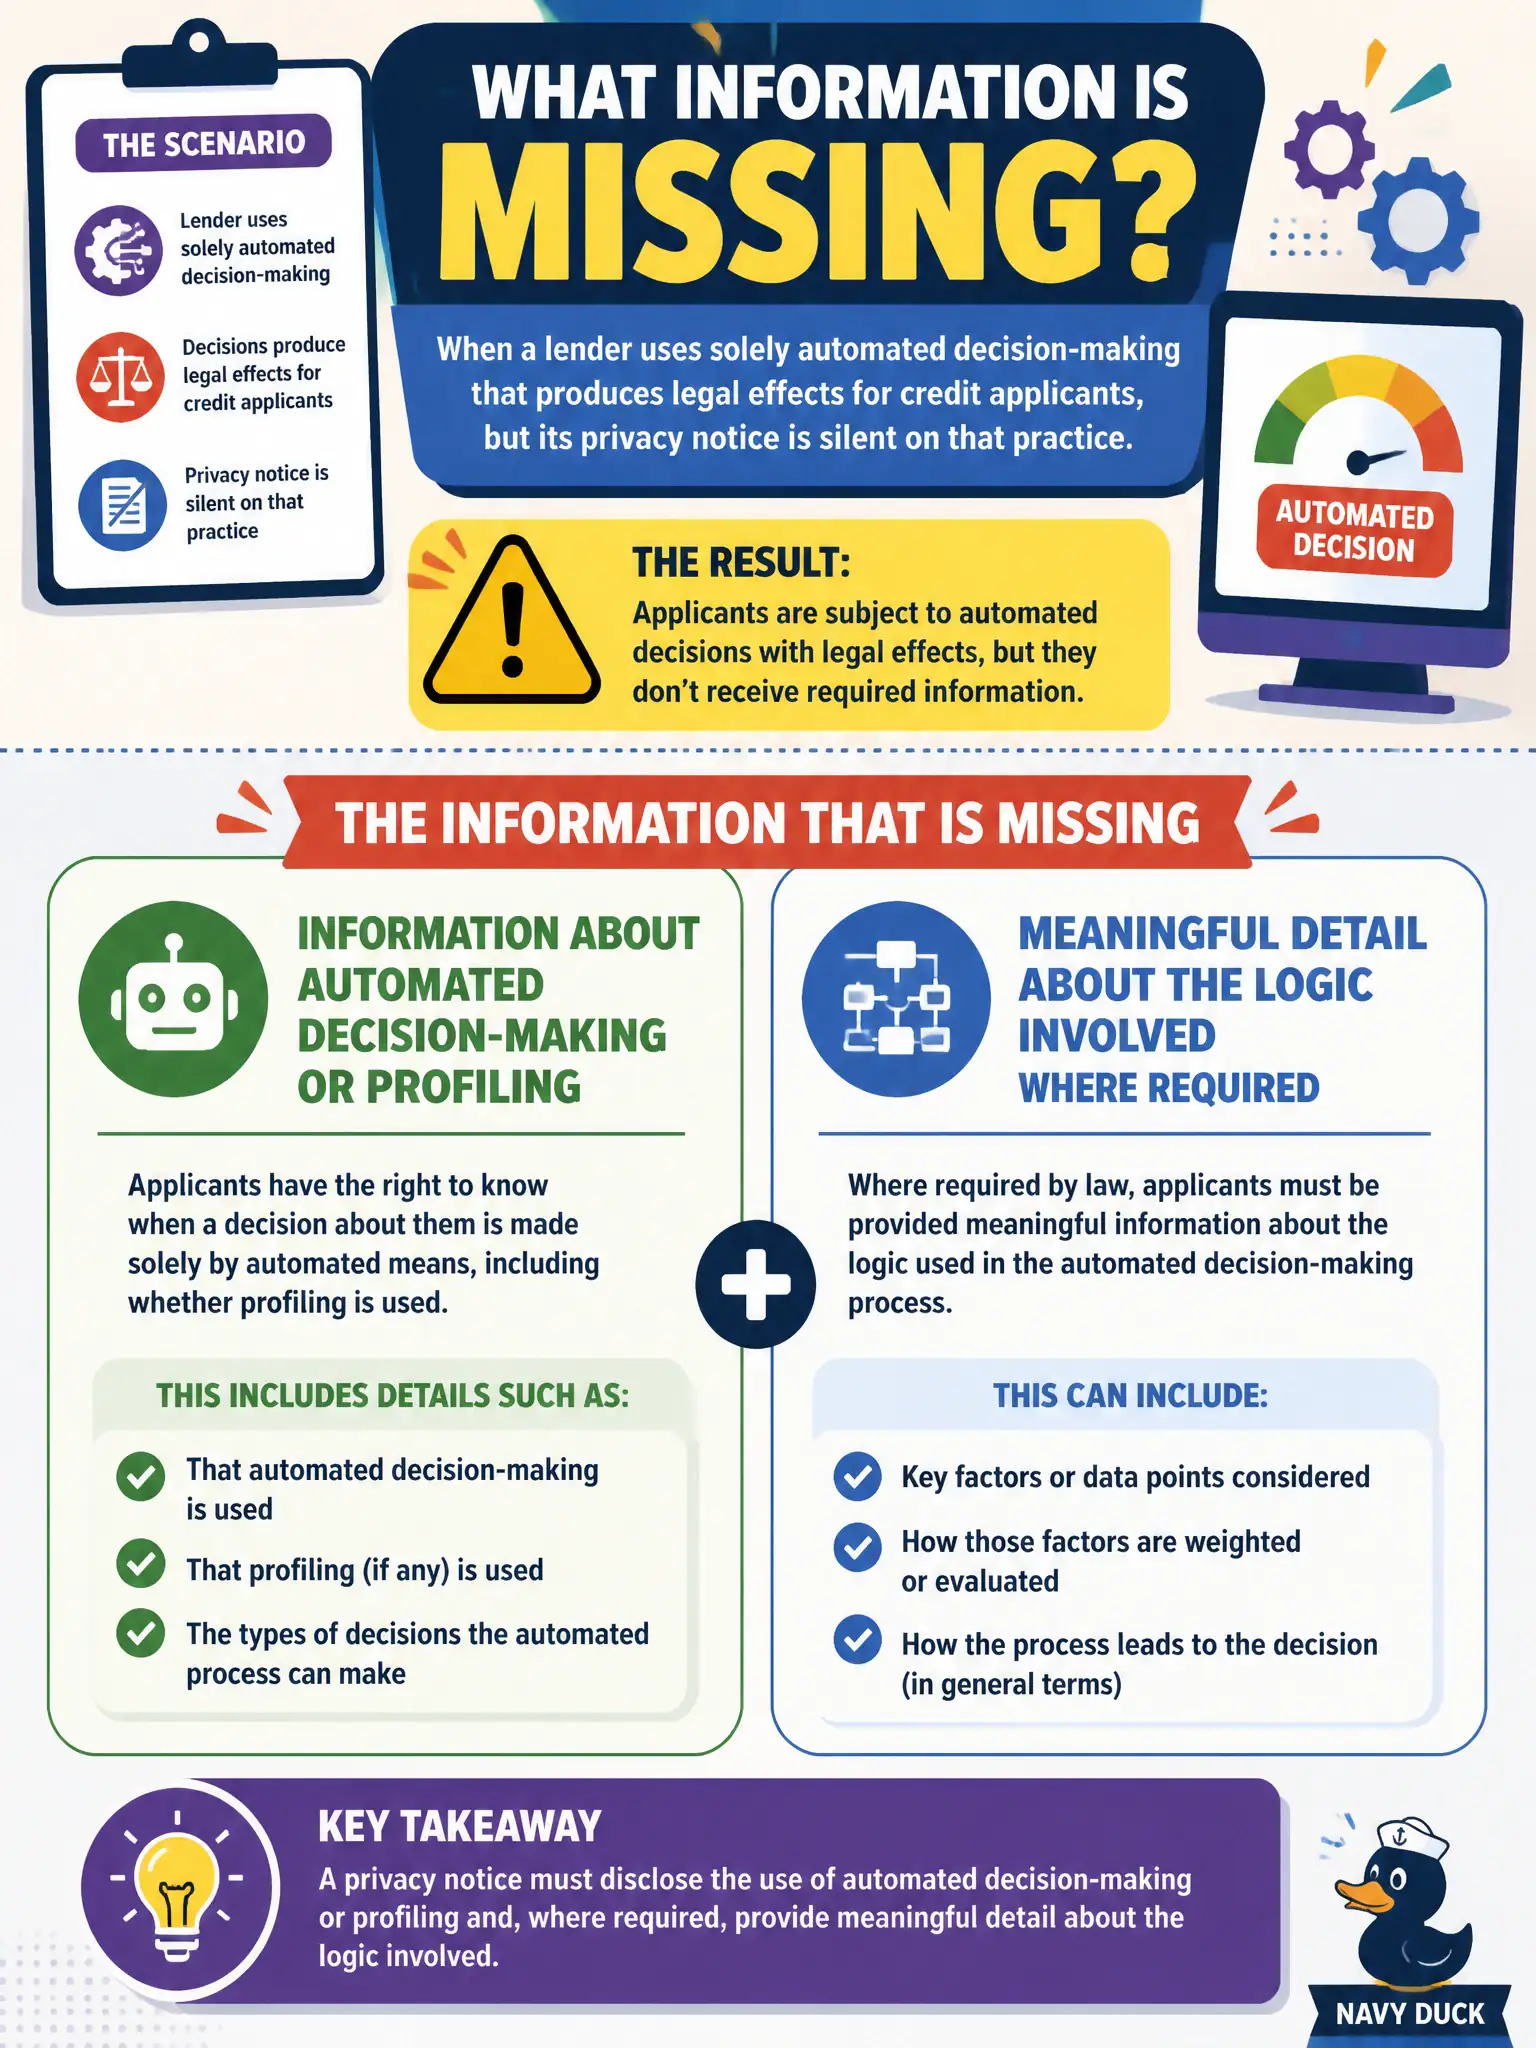
A lender uses solely automated decision-making that produces legal effects for credit applicants, but its privacy notice is silent on that practice. What information is missing?
Select an answer to reveal the explanation.
Short Explanation
If a machine alone can change someone's legal or similarly significant situation, say so in the notice—and give meaningful logic, not a black box shrug. Silence on ADM is a transparency miss.
Full Explanation
Where automated decision-making—including profiling—produces legal effects or similarly significantly affects the individual, Articles 13(2)(f) and 14(2)(g) require information about the existence of such decision-making and meaningful information about the logic involved, as well as significance and envisaged consequences. A lender using solely automated credit decisions without saying so in the notice withholds information applicants need to understand outcomes that can affect housing, work, and civic participation. Article 22 rights and safeguards also sit in the background of these disclosures.
Brand colours, notarised “no human ever” affidavits, and global SWIFT code lists are not the missing Article 13/14 content.
Exam caveat: “meaningful information about the logic” is not a demand to publish trade-secret source code; it requires intelligible explanation of main factors and consequences. Silence is the failure mode tested here.
Operational check: update the credit privacy notice and application journey with ADM/profiling disclosures, document human-review and contest paths where Article 22 applies, and verify adverse decision communications point back to that explanation.