
A financial services company is designing its internal compliance program. The Chief Compliance Officer explains the role of internal controls to the board. What is the fundamental, primary objective of these internal controls?
Select an answer to reveal the explanation.
Short Explanation
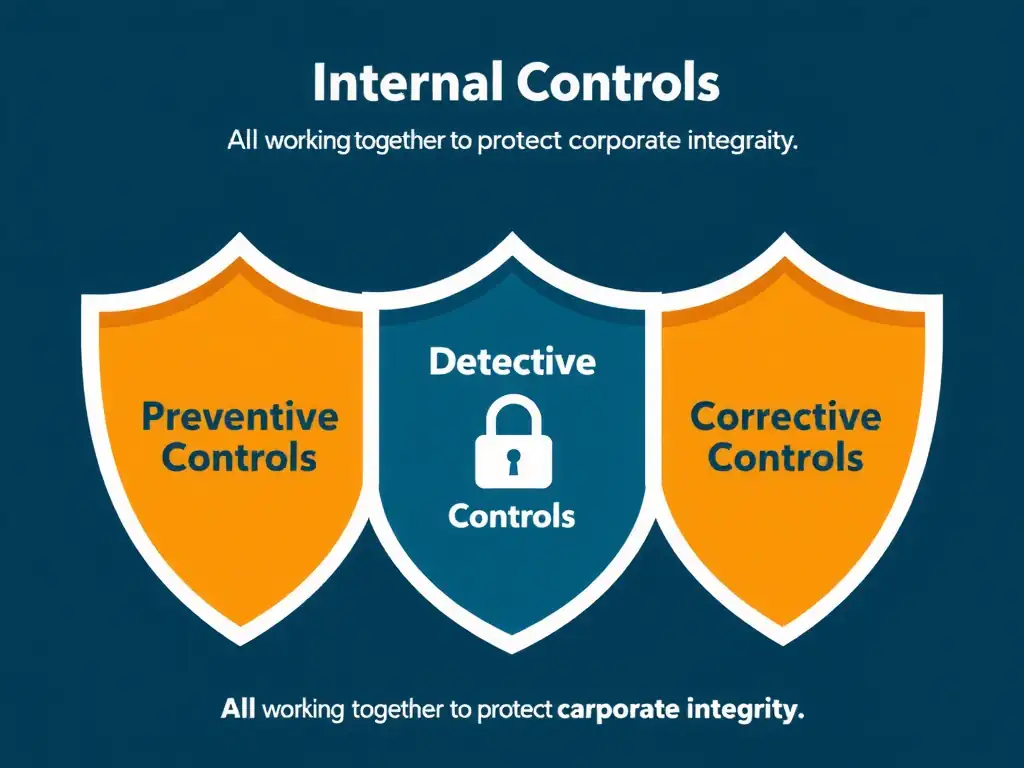
Think of internal controls like access control lists and firewalls on your network: they stop bad traffic from getting in, detect if something sneaky got through, and clean up the mess. That's exactly what internal controls do for business processes. They keep operations clean by stopping mistakes before they happen, catching them if they do, and fixing them fast.
Full Explanation
Internal controls are processes, policies, and systems designed to provide reasonable assurance regarding the achievement of objectives in operational effectiveness, financial reporting reliability, and compliance with laws and regulations. The COSO framework categorizes internal controls into preventive, detective, and corrective controls, which work together to safeguard assets and ensure compliance. The fundamental objective is to prevent, detect, and correct errors, operational failures, and compliance deviations. This objective is correct because the ultimate purpose of an internal control framework is to stop non-compliance and operational errors before they occur, detect them quickly if they do occur, and establish mechanisms to remediate and correct the issues. This three-tiered approach ensures that risks are managed within the organization's risk appetite. The idea that internal controls transfer all risk and legal liabilities onto the external auditing firm is incorrect because internal controls are the responsibility of the organization's management, not the external auditors. External auditors assess the effectiveness of controls but do not assume the company's liability or risk. The idea that internal controls replace executive management in making day-to-day commercial and strategic decisions is incorrect because internal controls are designed to guide and constrain operations to ensure compliance, not to make strategic business decisions or replace the executive team. The idea that internal controls purposely reduce corporate profit margins in order to minimize tax liabilities is incorrect because internal controls are meant to enhance operational efficiency and protect value, which supports profitability rather than seeking to reduce it.