
In SAS, which procedure is most appropriate for building a multivariate regression model when the number of predictors (p=500) greatly exceeds the number of observations (n=200)?
Select an answer to reveal the explanation.
Short Explanation
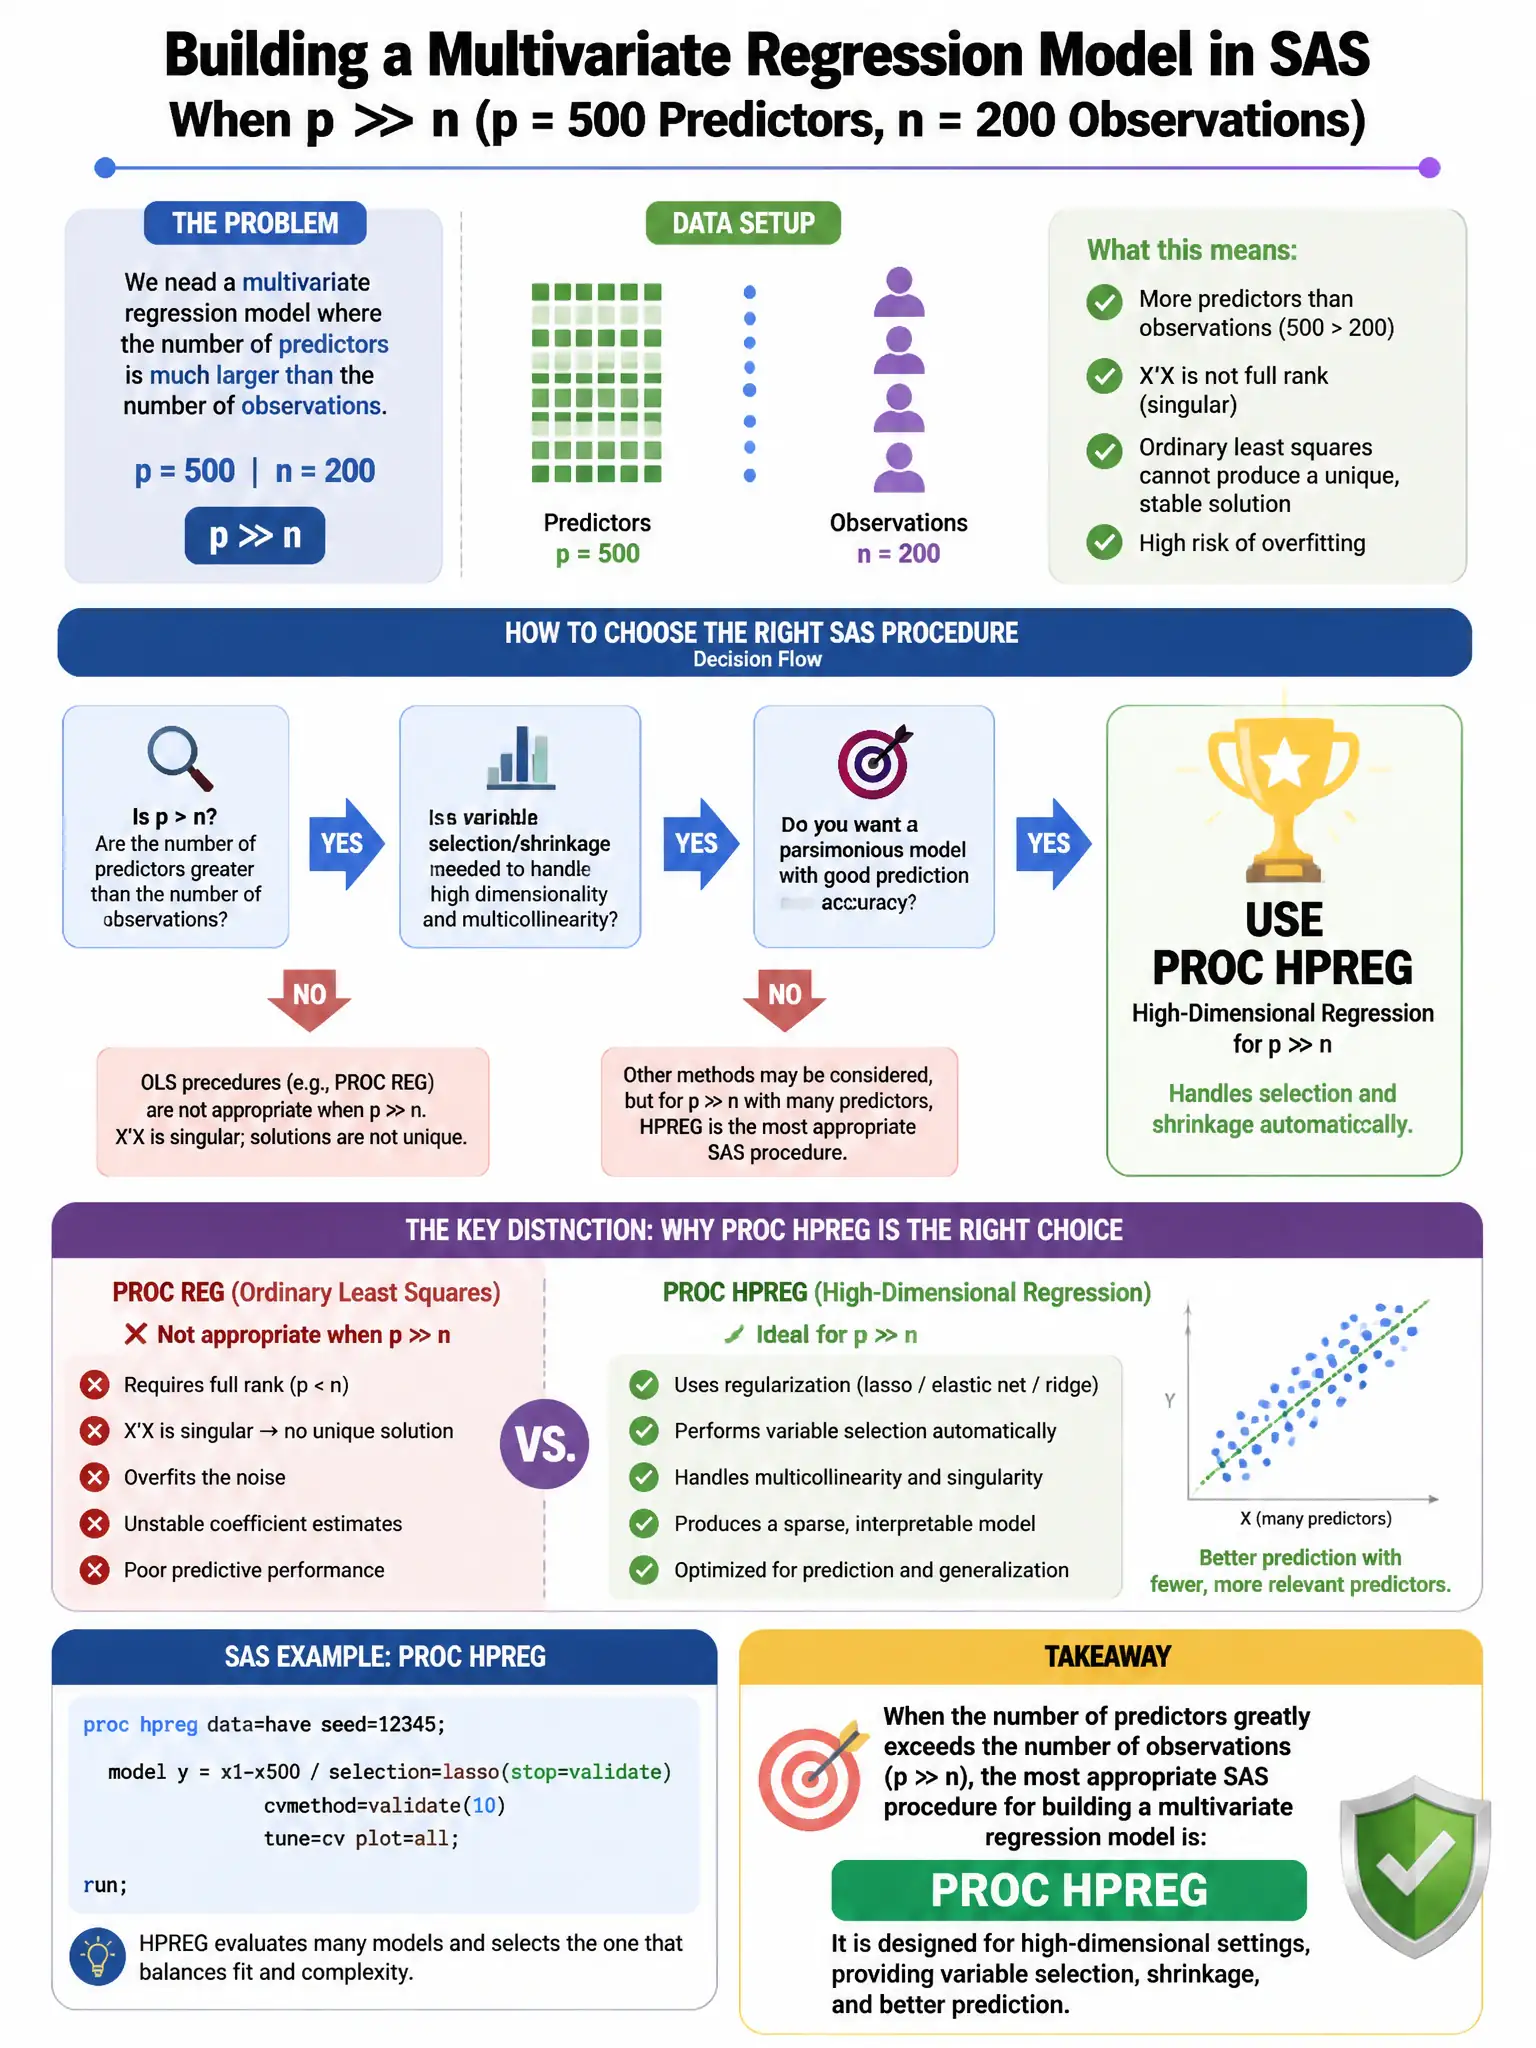
Here's the deal — when predictors outnumber observations, ordinary least squares is underdetermined and won't generalize. You need L1 regularization that shrinks coefficients and selects variables, so PROC HPREG with SELECTION=LASSO is the right move.
Full Explanation
When the number of predictors exceeds the number of observations, ordinary least squares regression is underdetermined and produces infinitely many solutions with perfect fit and no generalization. PROC HPREG with SELECTION=LASSO is appropriate because it applies L1 regularization, which simultaneously performs variable selection and coefficient estimation, finding a sparse solution that generalizes well even in high-dimensional settings. The PROC REG option with all 500 predictors in the MODEL statement is wrong because ordinary least squares with more predictors than observations is not uniquely solvable. The PROC FACTOR option that reduces 500 variables to components before regression is wrong because it reduces dimensionality, but principal components may not correspond to the most predictive features. The PROC HPFOREST option is wrong because, while random forests handle high-dimensional data, they are not immune to more predictors than observations; they require choosing VARS_TO_TRY carefully.