
A pension fund's investment technology committee is conducting due diligence on an AI vendor providing real-time risk scoring. The vendor is a Series B startup with $40M ARR and 18 months of runway. Which financial stability indicator should most concern the committee when assessing vendor viability for a 5-year production dependency?
Select an answer to reveal the explanation.
Short Explanation
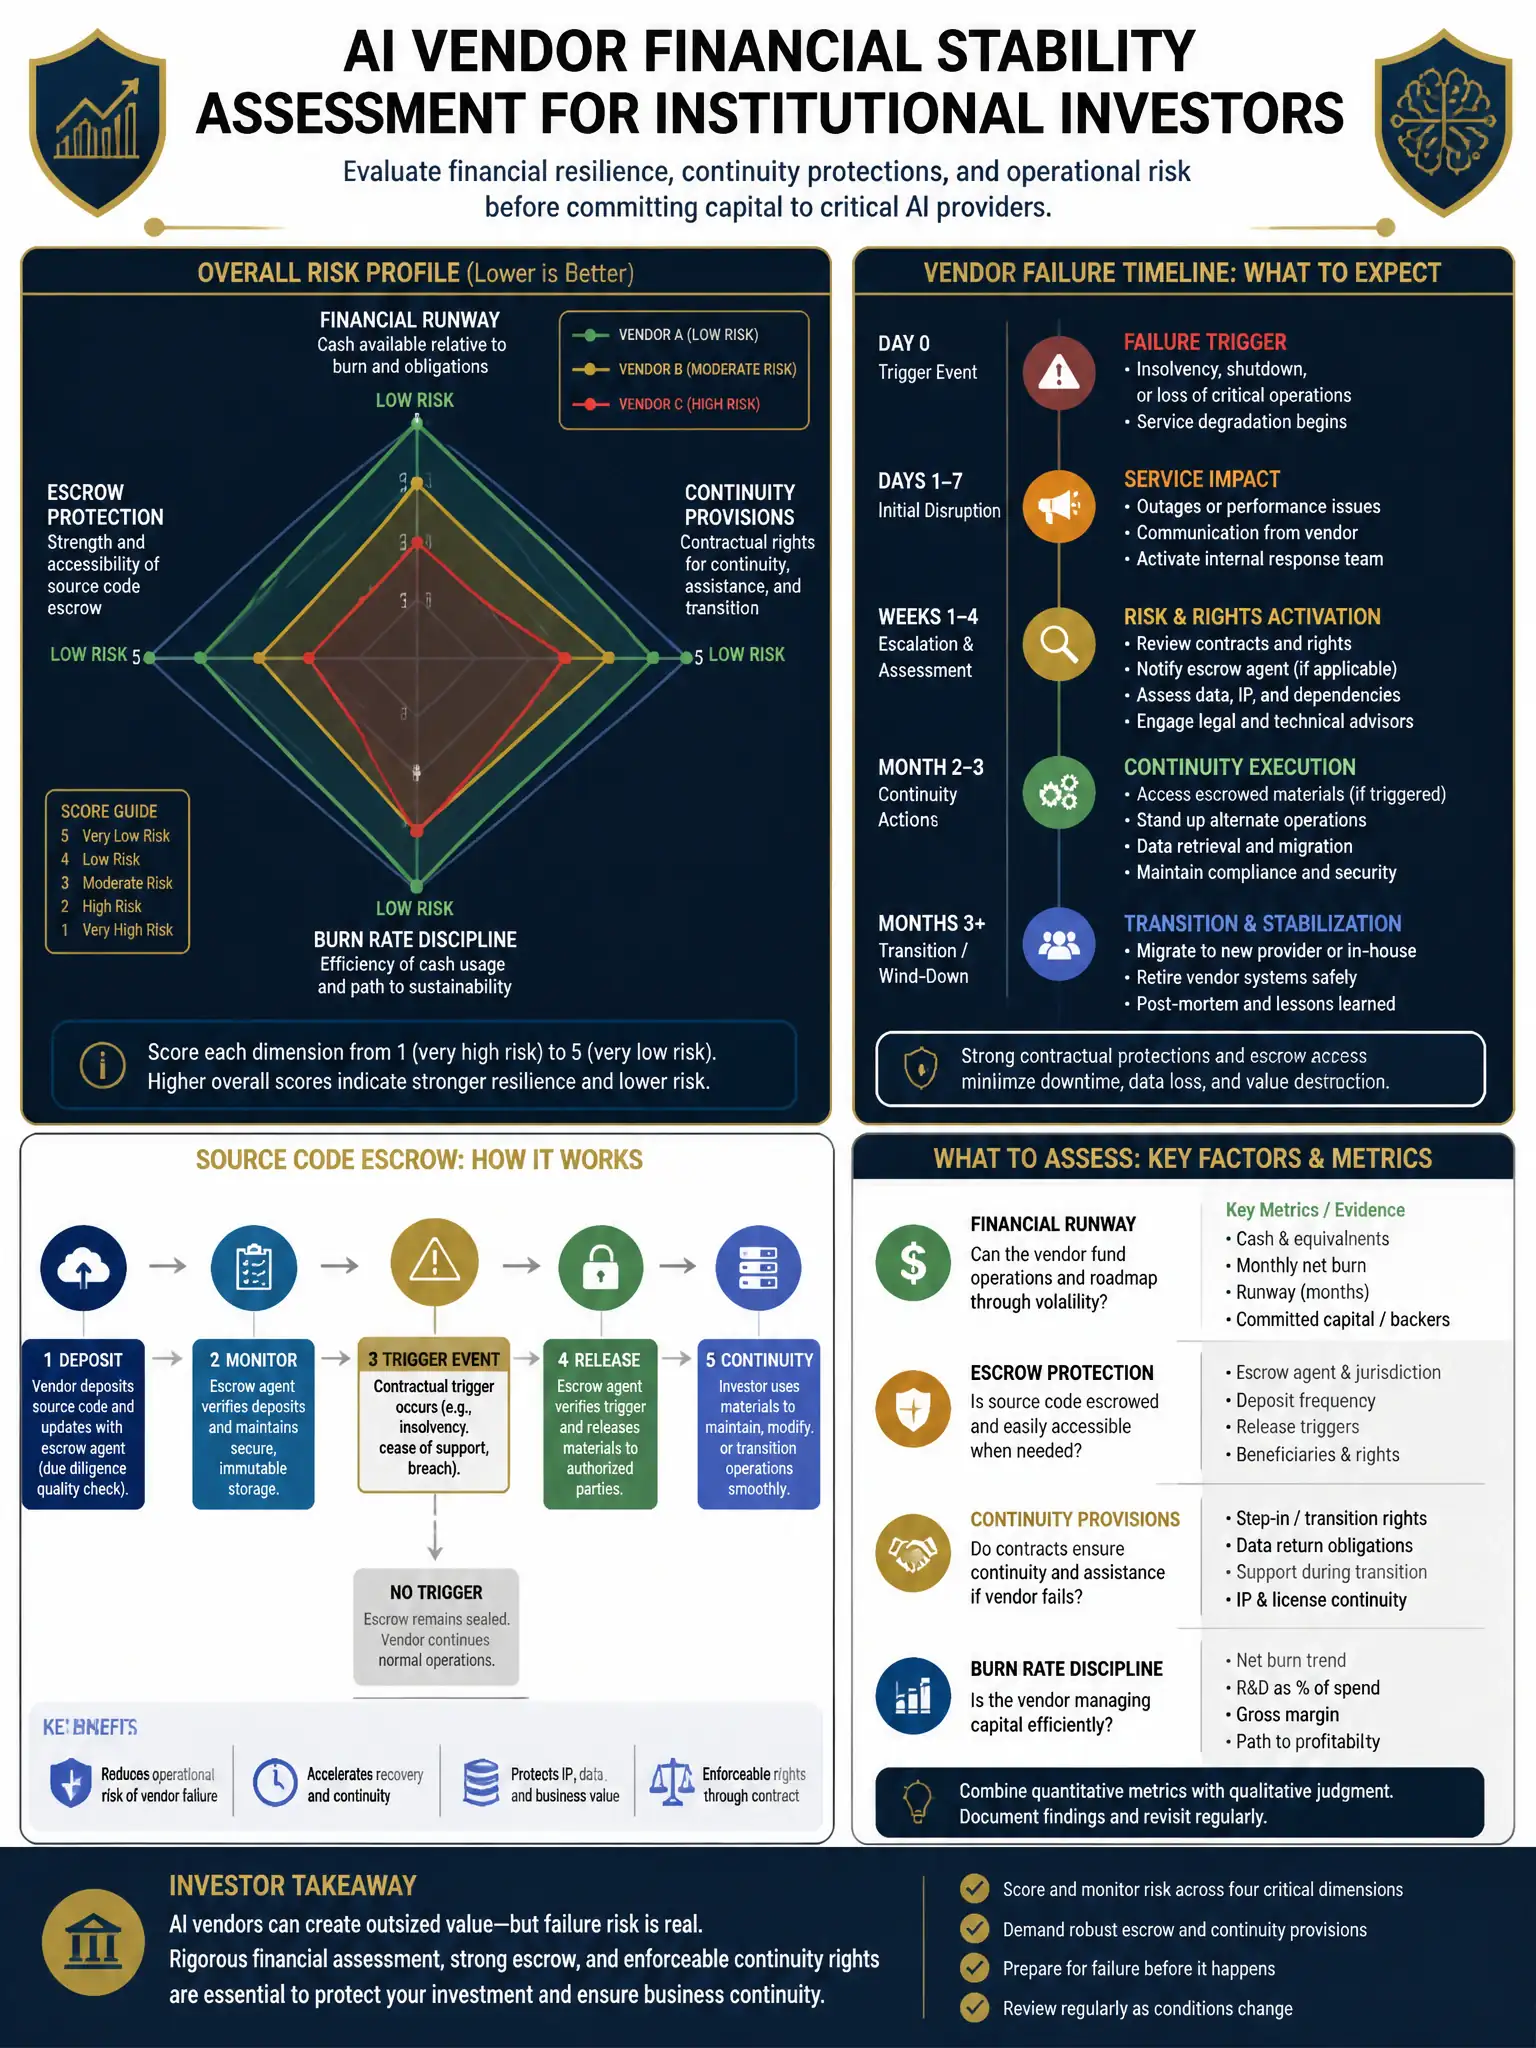
You should worry most about an 18-month runway with no source code escrow or business continuity provisions. That means if the startup runs out of money, the fund has no contractual way to keep the risk-scoring system running. It's not just a funding problem; it's an escape-hatch problem.
Full Explanation
For a regulated institutional investor building a 5-year operational dependency on an AI vendor, the key financial stability risk is not current profitability but survivability and continuity planning. Eighteen months of runway is a yellow flag for a company without a clear path to profitability or Series C commitment, but it becomes a critical red flag when no contractual protections exist to protect the fund if the vendor fails. Source code escrow agreements, in which the vendor deposits their codebase with a neutral third party such as Iron Mountain or NCC Group that releases it to customers upon defined trigger events such as insolvency, are standard risk mitigation in enterprise technology procurement. Similarly, business continuity clauses should require vendors to maintain 30-90 day operational bridges and notify customers of material financial deterioration. Without these provisions, the fund faces operational disruption with no legal recourse at the worst possible moment. The gross-margin concern, citing a 72% gross margin below the 80% benchmark typical of mature SaaS companies, is a secondary benchmark concern. A 72% gross margin in a growth-stage AI company often reflects appropriate infrastructure investment, not mismanagement. The per-API-call pricing concern, choosing per-API-call pricing rather than a flat annual subscription, is a commercial negotiation point, not a stability indicator. The founder-exit-history concern, noting that the founding team previously exited one company via acquisition rather than IPO, is a weak signal at best; acquisition exits are common, respected outcomes in venture-backed technology and do not predict abandonment behavior. The CFA Institute's Operational Due Diligence framework and ILPA's Operational Due Diligence Best Practices both emphasize contractual continuity provisions as primary considerations when evaluating technology vendors. Exam caveat: CFIA candidates should memorize the escrow-plus-continuity combination as the institutional standard for vendor risk mitigation.